Brent Broke, the Contracts Sat Still
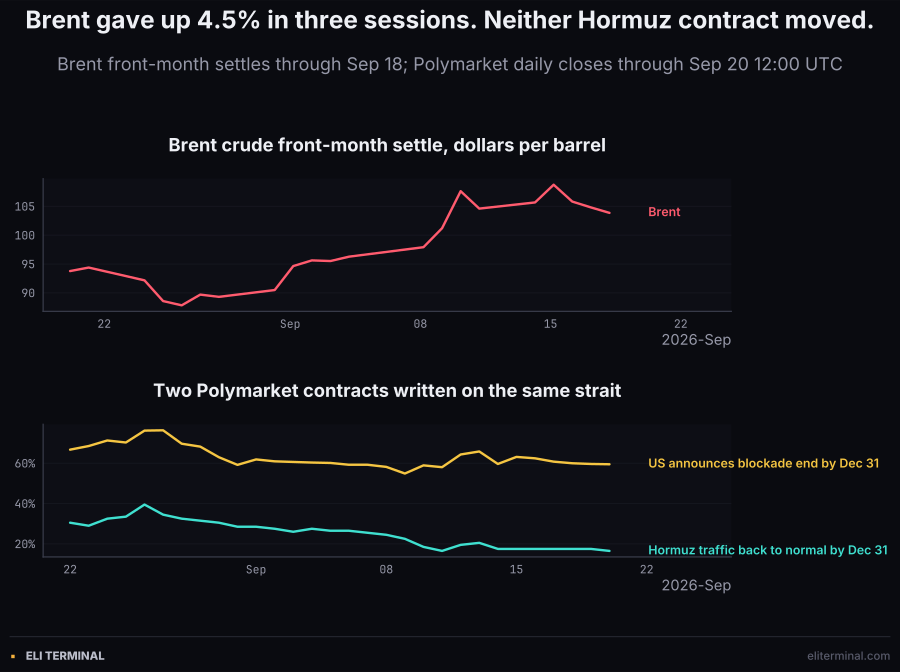
Brent front-month settles through the September 18 close; Polymarket daily closes through September 20, 12:00 UTC.
Saudi Aramco pushed 2.8 million barrels a day through a strait that has been shut for 203 days. Brent fell 4.5%. The Hormuz reopening contract sat at 17.5% for five straight days.
Brent front-month settles through the September 18 close; Polymarket daily closes through September 20, 12:00 UTC.
Four commodity vessels were detected moving through the Strait of Hormuz on Thursday. On the same water, over the six days to September 17, satellite imagery showed Saudi Arabia pushing 2.8 million barrels a day through the strait, against roughly 700,000 barrels a day in August. Both figures come from CNBC's September 18 market report.
Four hulls, four times the oil. That is what the week's biggest story looked like, and almost nobody wrote it down.
What everybody did write down was the shooting. Houthi forces fired drones and ballistic missiles at Khamis Mushait, Abha and Taif; Saudi Arabia's East-West pipeline, the only major overland route around Hormuz, stayed shut after a drone strike on a pumping station; NPR counted some 125,000 Yemenis displaced by the advance down the Red Sea coast.
Brent fell 4.5% across those three sessions, from a 108.75 settle on September 15 to 103.87 on September 18. It did that because the oil market was reading a tanker tracker and the headlines were reading a war.
The pipeline was the whole bull case. It carries up to 7 million barrels a day from the eastern oilfields to the Red Sea coast, and Riyadh shut it on September 11 as what it called a precautionary measure after a drone strike from Iraq hit a pumping station.
Then the US Energy Secretary went on television. Chris Wright told CNBC on September 15 that the outage would be a brief and temporary interruption, one that would be "measured in days."
Andy Lipow, who runs Lipow Oil Associates, had looked at the same event through satellite pictures of the wreckage and reached the opposite conclusion. "Judging from the on-line pictures, it will take months to repair," he said.
Crude went with Wright. WTI for October settled at 105.88 that day and Brent closed at 108.75, the high-water mark of the week, and every session after it went down.
At 10:15 AM Eastern on September 16, which is 14:15 UTC, Yongchang Chin, Alfred Cang and Salma El Wardany reported for Bloomberg that Saudi Aramco had sold about 20 million barrels to Asian refiners that week, for loading from the Gulf of Oman on a ship-to-ship basis over September and October. Buyers included Chinese state-owned and independent processors. Aramco declined to comment.
The mechanism matters more than the volume. Selling from outside the strait means the cargo changes hands past the dangerous water, so the buyer never owns a barrel that has to make the transit, and the seller runs the risk on short shuttle runs instead of on laden supertankers.
BNO, the fund that holds Brent futures and trades on New York hours, opened its 14:30 UTC candle at 62.50 and closed it at 61.59. That is 1.5% in the hour after the Bloomberg story, the worst hour of its session, and the low of the day printed in the hour after that.
Brent settled September 16 at 105.83, down 2.7% from the previous close. Two hours and twenty minutes after the first story, at 16:35 UTC, El Wardany filed again for Bloomberg: Aramco was seeking to return about half the pipeline's capacity within days, and full capability in about six weeks.
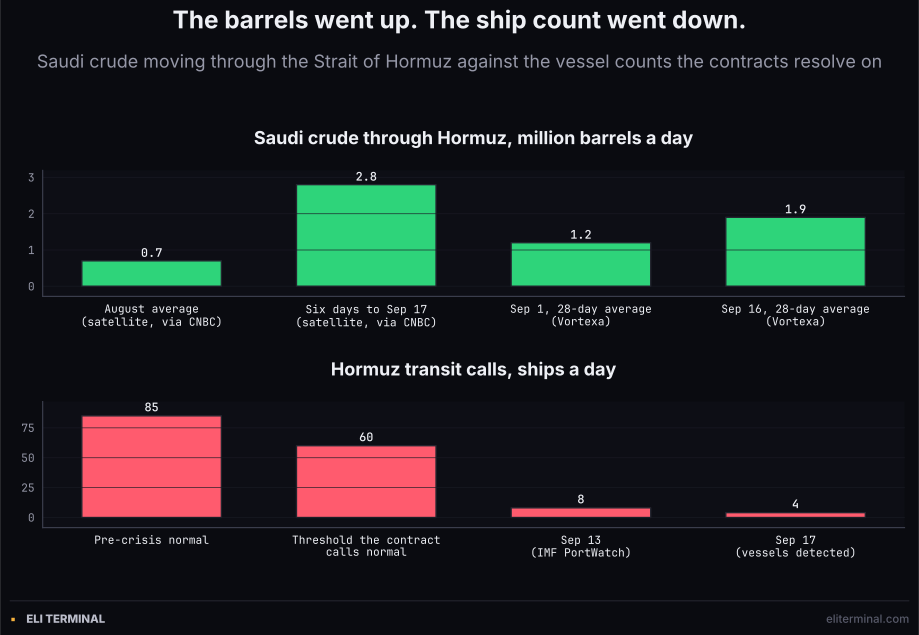
Satellite figures via CNBC; 28-day transit averages from Vortexa; ship counts from IMF PortWatch. The barrels and the hulls moved in opposite directions.
Two independent trackers say the same thing in different units. AGBI reported that Vortexa's 28-day moving average of Hormuz transits rose from 1.2 million barrels a day on September 1 to 1.9 million on September 16, while Kpler put ship-to-ship transfers in the Gulf of Oman at 2.7 million barrels a day in September against 1.5 million in August.
The shuttles run under US Navy escort from Saudi terminals out to larger tankers waiting in the Gulf of Oman. It is an expensive, ugly, entirely functional way to defeat a blockade, and it does not require the strait to reopen.
On September 16, in Beijing, Iranian foreign minister Abbas Araghchi told his Chinese counterpart Wang Yi that a reopening had been agreed. TASS quoted him saying Iran "has already agreed with Oman on a plan to reopen the Strait of Hormuz and believes that the US side must faithfully fulfill all the commitments it has undertaken."
Taken at face value that sentence ends the largest supply disruption in the history of the oil market. The Polymarket contract on Hormuz traffic returning to normal by December 31 closed that day at 17.5%, exactly where it had closed the day before, and exactly where it closed on the 17th, the 18th and the 19th.
Five consecutive daily closes at the same number, on a contract carrying $11.9 million of lifetime volume, is not a thin market shrugging. It is a deep one telling you the statement did not change the probability of the thing.
The contract is specific about what the thing is. It resolves Yes only if IMF PortWatch publishes a seven-day moving average of transit calls for the strait "equal to or above 60" on any date before the deadline. PortWatch recorded 8 transits on September 13 against a pre-crisis baseline of about 85 a day. The threshold is seven times current reality, and a foreign minister's travel readout does not close that gap.
There is a second Hormuz market, and it is the popular one. It asks whether the United States will announce an end to the naval blockade that Trump reinstated on July 13, the one that took effect the following afternoon and came with a charge on commercial shippers crossing the strait.
Its resolution text runs to nine paragraphs of careful drafting about what counts as an official statement, which agencies qualify, and why leaks and satire do not. Then it says this:
"Once a qualifying announcement is made, this market will resolve to 'Yes' regardless of whether it is later reversed, or whether the blockade actually ends in practice."
That is not a defect. It is a deliberate, well-drafted contract on a press release, and it is honest about being one. The trouble is what happens when a reader treats it as a gauge of the war.
Across the week that Saudi Arabia quadrupled its barrels through the strait, the December 31 announcement contract went from a 63.2% close on September 15 to 59.5% on Sunday, a drift of under four points on $2.0 million of lifetime volume. The physical world changed by a factor of four and the number moved less than a rounding error in a Fed forecast.
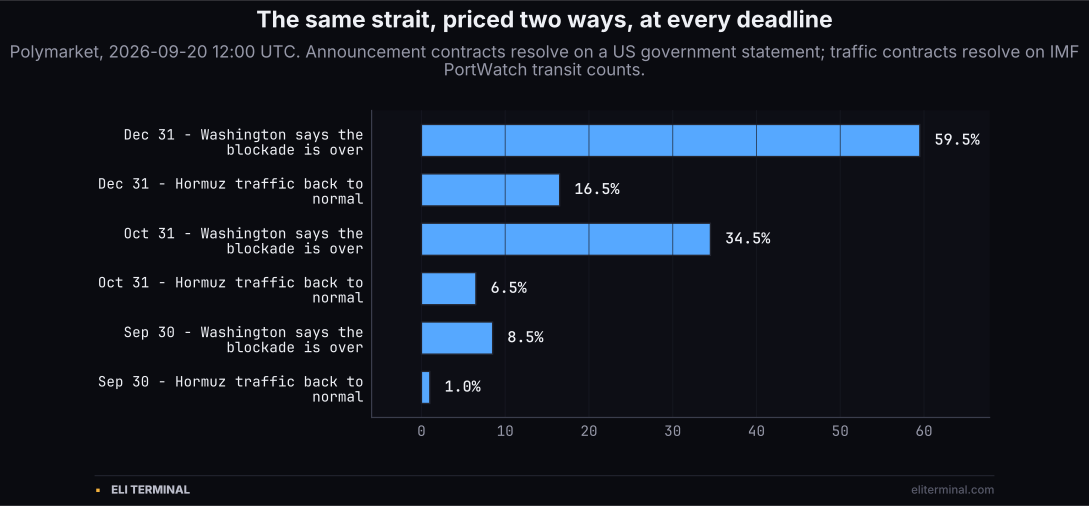
Polymarket, September 20, 12:00 UTC. At every deadline the announcement trades at three to eight times the barrels.
Line the two families up by deadline and the spread is the whole argument. By December 31 the announcement trades at 59.5% and the traffic at 16.5%, a gap of 43 points. By October 31 it is 34.5% against 6.5%. By September 30, ten days out, it is 8.5% against 1.0%.
Read together, those prices say something coherent and fairly bleak: traders think it is more likely than not that Washington declares this over by the new year, and they think the odds are roughly one in six that the ships come back.
The cleanest test of whether prediction markets can see barrels is a contract written on barrels, and there is one 1,500 miles away.
Houthi forces took the Red Sea port of Mokha and several islands near the Bab el-Mandeb strait this month, which is the sort of headline that should price a closure. NPR reported on September 18 that the shipping firm Windward measured daily transits falling from 35 before the advance to 25 after, then recovering to 45 on Sunday.
The contract on Bab el-Mandeb being effectively closed by September 30 went from a 5.0% close on September 15 to 3.5% on Sunday, with a 2.3% print on the 19th. It tracked the recovery in the hulls, because closure is a physical condition and the contract is written on the physical condition.
So the machinery works. Markets written on the world move with the world. The Hormuz announcement contract did not move because nothing it measures happened: no one from the President, the Pentagon, State or Central Command said the blockade was over, and Aramco's shuttle fleet is not an official channel.
Saudi Arabia was struck repeatedly on its own soil. Houthi forces killed one person in Taif governorate on Friday when a drone was intercepted, and the group accused Saudi Arabia of 26 strikes in 24 hours on areas it controls. War-risk insurance on a single very large crude carrier through Hormuz is running around 40 times pre-crisis rates.
Against all of that, Brent lost 4.5% in three sessions and the volatility index closed the week at 14.81, its lowest close since September 4. Energy equities moved less than the barrel did: XLE gave up 2.5% over the same three sessions while Brent gave up 4.5%, which is what happens when the move is a logistics story rather than a demand story.
The weekly market on how many ships transit Hormuz between September 14 and 20 is priced for somewhere between 20 and 29 for the entire week, with about $33,000 across all six legs. That is a handful of people arguing, not a market, and it should be read as such. It is also the only listed contract anywhere that would have paid a reader for noticing what Aramco did.
There is a version of this week in which a trader reads the pipeline headlines, buys the blockade contract as a war hedge, watches Brent fall 4.5% around them, and finishes flat. The contract did its job perfectly. It was just never a bet on the strait.
▪ eli terminal · Research desk · Published 2026-09-20 12:00 UTC
Futures anchored to the 2026-09-18 21:00 UTC settle. Prediction-market levels are Polymarket closes to 2026-09-20 12:00 UTC.
Not investment advice.