Thursday September 10, 2026 • PPI Day, Crude Back Above 100
Oil Jumps 6.7% Past 102, Houthis Take Mokha, Apple Rises 3.6%
WTI crude jumped 6.7% after Houthi forces took the Red Sea port of Mokha, the September Fed hike bet rose 11 points on a producer price report whose core undershot, and the energy stock fund still closed lower.
Thursday 4pm close
S&P 500 7,591.70 −0.58%
·
NASDAQ 26,081.72 −0.65%
·
DOW 52,064.10 −0.60%
·
VIX 17.84 +8.4%
The barrel and the oil patch
WTI 102.48 +6.69%
·
BRENT 107.63 +6.34%
·
XLE 64.93 −0.58%
·
XOM 165.23 +0.61%
Rates and the Fed bet, 1 day
2Y 4.56% +13bp
·
10Y 4.95% +12bp
·
10Y REAL 2.55% +9bp
·
SEPT HIKE ODDS 64% +10pts
Metals and single names
GOLD 4,364.50 −1.17%
·
COPPER 6.467 −4.95%
·
AAPL 326.57 +3.56%
·
ORCL 152.94 −5.38% +6.2% after hours
WTI crude, energy stocks, gold and the S&P 500 by the quarter hour, September 10
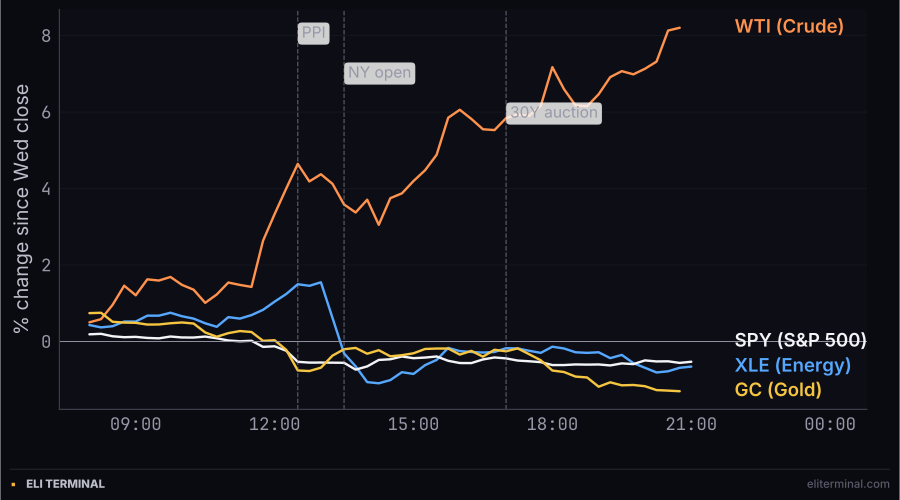
Crude ran all day. The S&P fund took its loss before 13:30 UTC and went sideways; the energy fund gave up its pre-market gain in the first fifteen minutes of trading.
The S&P 500 lost all of Thursday's decline before the opening bell
758.03 at the open, 757.83 at the close. The SPDR S&P 500 fund finished the regular session 20 cents below its first trade, and its entire 0.60% decline from Wednesday was in place by 13:30 UTC. The Nasdaq-100 fund did slightly better than flat inside the session, from 707.55 at the open to 708.69, and still closed down 1.06%.
One pre-market hour did the damage. Between 11:45 and 12:45 UTC, WTI crude went from 97.42 to above 100, the August producer price report printed, and the S&P fund slid from 762.53 to 758.18. The six and a half hours of trading that followed added another 3% to crude and almost nothing to the index.
Houthi forces took Mokha, and crude fell for seven hours overnight
Houthi fighters took the Red Sea port of Mokha on Thursday after about a week of fighting, pushing the Giants Brigades and Nation's Shield units south toward Dhubab. "With the fall of Mokha, Bab Al Mandeb can be considered under the administration of our forces," a Houthi commander told The National, while the group's spokesman Mohammed Abdul Salam told Al Jazeera that navigation through the strait remains safe.
The Polymarket contract on Bab el-Mandeb being effectively closed by October 31 went from 9.5% just before midnight UTC to 18% by 03:15 UTC, hours before any New York desk opened. WTI went the other way over the same stretch, sliding from 97.14 at 23:00 UTC Wednesday to 95.43 by 06:15 UTC while the closure odds doubled.
Crude also slept through a Wednesday-evening Wall Street Journal report that Vice President JD Vance and Secretary of State Marco Rubio had told President Trump in private the Iran war could last through January 2029. Hours earlier, boarding Air Force One for Dallas, Trump had told reporters "the war will end immediately after the election."
Traffic through the strait collapsed on the day. Only 12 vessels had crossed Bab el-Mandeb by 6pm Thursday against 30 on Wednesday, and a single ship entered the Red Sea against 17 the day before, The National reported.
Crude's run started with Europe and crossed 100 in the PPI bar
95.43 at 06:15 UTC was the low. WTI climbed as European desks opened, gained 1.2% in the quarter hour starting 11:45 UTC with no dated headline in that window, and printed 100.51 in the 12:30 UTC bar that carried the producer price release.
Saudi Arabia told OPEC on Thursday that its August crude output fell 1.9 million barrels a day to 6.238 million, the lowest the kingdom has reported since 1990, Bloomberg reported. WTI settled at 102.48, its highest settlement since May 19, and kept climbing after the settle to 103.93 by 20:45 UTC; Brent settled at 107.63 after trading above 108 in the afternoon.
A producer price report with a softer core lifted the Fed hike bet 11 points
Final-demand producer prices rose 0.4% in August, in line with forecasts, for a 5.4% annual rate against 5.3% expected and 4.8% in July, the Bureau of Labor Statistics said at 12:30 UTC. Energy rose 4.2% and made up more than three-fourths of the monthly gain, with diesel up 24.1%. The core index excluding food and energy rose 0.2% against a 0.3% forecast.
Kalshi's contract on a 25 basis point hike at the September 16 meeting sat at 54% in the hour before the release and 65% in the hour after, closing at 64%. Polymarket's no-change contract fell from 47.5% to 37.5% by 12:45 UTC. The only upside surprise in the report was an annual headline rate carried by fuel, and weekly jobless claims released in the same minute came in at 206,000 against 205,000 expected.
Bab el-Mandeb closure odds, WTI crude and the September Fed hike bet, hourly, September 9 to 10
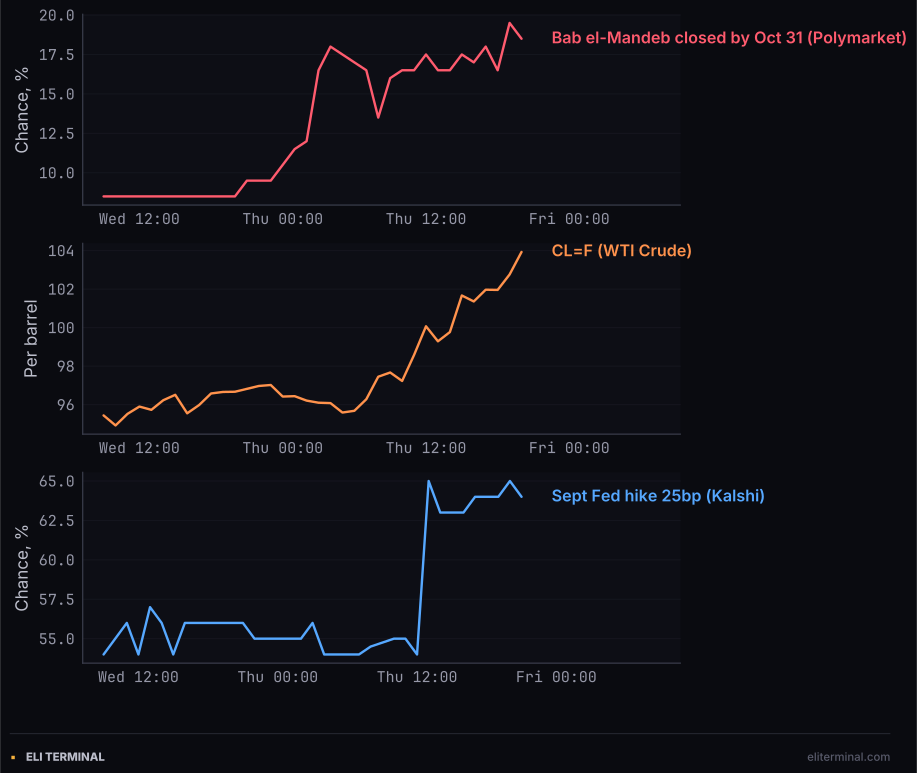
The closure market repriced while crude slept. Crude and the Fed bet moved together, eight hours later.
Real yields carried the 10-year Treasury to 4.95%, its highest since October 2023
Nine of the 10-year yield's 12 basis point rise came from the inflation-protected real yield, which climbed to 2.55%. The 10-year breakeven rate, the bond market's own inflation price, rose 3 basis points to 2.40%. The two-year and five-year yields rose 13 and 14 basis points; the 30-year rose 9.
That shape belongs to a repricing of the next few Fed meetings, not to a market bracing for years of higher inflation, which would have lifted breakevens and the long end hardest. Gold, the asset real yields hit most directly, fell 1.17% to 4,364.50 on a day of war escalation and falling stocks, and silver lost 5.4%.
Where Thursday's Treasury selloff landed, in basis points
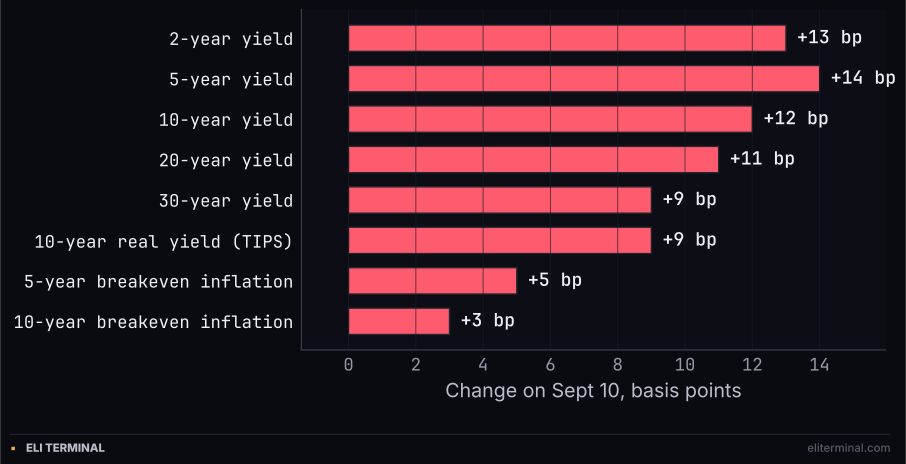
The front and the belly moved most. Inflation compensation barely moved.
The 10-year had already risen 4.4 basis points by 12:20 UTC, before the PPI, and added 3.7 more by 12:55 UTC. Wednesday night in Dallas, Trump promised "a dividend to every adult citizen in the United States of America" of 5,000 dollars if Republicans hold both chambers, a pledge CNBC costed above 1 trillion dollars, and he reposted the clip to Truth Social Thursday morning; the long end, where a deficit worry would show first, rose least.
The Treasury sold 22 billion dollars of 30-year bonds at 17:00 UTC at 5.308%, 2.7 basis points below the when-issued yield, with a 2.61 bid-to-cover ratio against a six-auction average of 2.38 and dealers left with just 2.2%, investingLive reported. The 10-year yield, 4.916% when those results crossed, still rose to 4.950% by 18:25 UTC as WTI stepped from 101.97 to 102.94 in the 18:05 and 18:10 UTC bars. The Treasury also bought back 5.187 billion dollars of 10- to 20-year debt, short of the 6 billion dollars it had offered to take in the first operation of its enlarged program.
Energy stocks fell on a 6.7% oil day, the third straight session they trailed the barrel
The Energy Select Sector SPDR fund traded as high as 66.29 before the open, 1.5% above Wednesday's close, then gave all of it back in the first fifteen minutes of the session, falling to 65.11 while WTI held near 99.50. It closed at 64.93, down 0.58%, with Exxon Mobil up 0.61% and Chevron down 0.49%.
Tuesday the fund rose 1.11% against crude's 1.69%. Wednesday it rose 0.83% against 3.25%, and Thursday it fell against 6.69%. From Friday's close through Thursday, WTI is up 12.0% and XLE is up 1.4%: the holders of the producers have declined to pay for the price the futures market is setting.
WTI crude, the energy fund, Exxon Mobil, gold and the S&P 500 over the past month
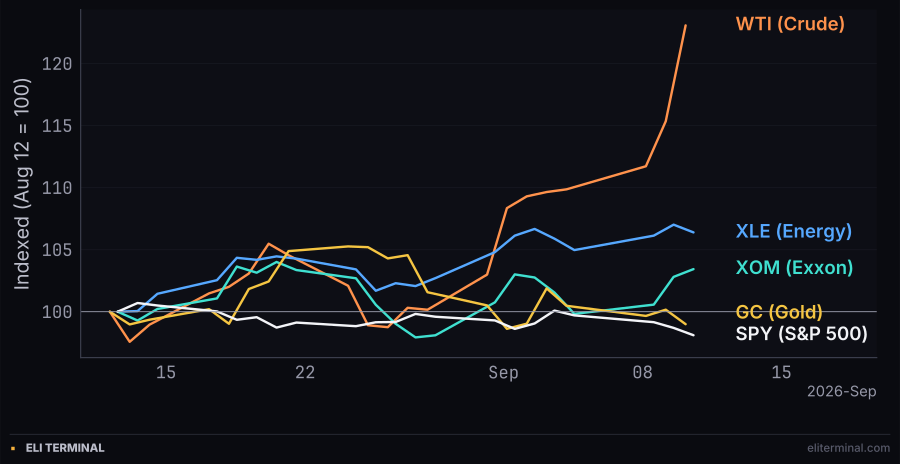
Crude is up 23% in a month; the energy fund is up 6%, and only about 1.5% since August 31.
Copper fell 5% after Reuters reported the White House had stalled its refined copper tariff
Reuters reported early Thursday that the White House had not decided on tariffs for refined copper, a plan Commerce Secretary Howard Lutnick was asked to weigh at 15% from January 2027 rising to 30% in 2028, as officials worried about manufacturing costs before the midterms. COMEX copper fell from 6.828 to 6.577 between 09:45 and 10:30 UTC, and Freeport-McMoRan dropped from 75.30 to 70.99 in pre-market trading over the same 45 minutes.
COMEX copper closed down 4.95% at 6.467 a pound, and Freeport finished about 7% lower. London copper was down a smaller 3.1% by mid-morning in New York after touching a record 14,875 dollars a ton earlier in the same session, 24/7 Wall St. reported, and the American contract, the one carrying the tariff premium, fell further.
Apple added more than 160 billion dollars as Oracle reversed a 5.4% slide after the bell
Apple opened at 316.67 and closed at 326.57, up 3.56% and 17 cents below its session high, the day after unveiling its first foldable phone, the iPhone Duo, at 1,999 dollars. No Apple announcement landed Thursday. Citi and Morgan Stanley reiterated their ratings and Bank of America trimmed its target to 370 from 380, and the stock rose anyway, building its gain inside the same regular session in which the S&P fund went nowhere.
Into its earnings, Oracle fell 5.38% to 152.94 on the day the 10-year hit its highest level since 2023. Its fiscal first-quarter release crossed at about 20:10 UTC: revenue up 30% to 19.3 billion dollars, cloud infrastructure up 121% to 7.4 billion, remaining performance obligations of 664 billion, and a fiscal 2027 outlook of at least 90 billion dollars in revenue.
The same release showed free cash flow of negative 5 billion dollars and 20 billion dollars of common stock sold through an at-the-market program, and said that for the new contracts "there is no incremental impact on its plans to raise capital." Oracle traded at 162.30 in the 20:10 UTC bar and 162.48 by 20:55 UTC, up 6.2%. Adobe, which raised its full-year guidance in the same window, fell about 2% after hours to near 243.
The 2.37% Nvidia lost, closing at 218.36, came before 13:45 UTC; the shares then held between roughly 217.4 and 218.8 from there to the close. At Goldman Sachs' Communacopia conference Thursday, Jensen Huang said unconstrained demand was growing more than 100% and told the room "we should just take a pause and acknowledge that I was right," per a transcript. Micron fell 4.9% to 977.41, its steepest pre-market drop coming in the PPI bar.
Anthropic said a northern Yemen cell used Claude Code on missile guidance the day Mokha fell
Anthropic published a threat-intelligence report Thursday describing a small cell in northern Yemen, territory the Houthis control, that used Claude Code to write guidance, navigation and control software for three programs: a guided rocket built on a phone-class flight computer, a multistage ballistic missile with a range goal above 2,000 kilometers, and a missile family that included a hypersonic glide vehicle variant. Anthropic did not name the group, banned the accounts, and wrote: "We do not have evidence the actors succeeded in fielding an operational device; but they did test-fire a guided rocket."
Defense stocks split on the day the Houthis took Mokha and the report landed. Lockheed Martin rose 1.08% and Northrop Grumman 0.66%, while the iShares U.S. Aerospace & Defense fund fell 0.51%.
Friday's CPI and the September 16 Fed decision test the oil-to-Fed channel next
August consumer prices print at 12:30 UTC Friday, with the consensus at 0.4% on the headline and 0.2% on core, month over month. Thursday already showed how the hike market treats a fuel-driven headline paired with a soft core: it added 11 points.
The Fed announces its decision at 18:00 UTC on Wednesday, September 16, with the hike contract at 64%. Polymarket's contract on an Iran-Oman agreement over Hormuz by September 14 closed at 8.5%, down from 12% Wednesday night, and the one on Hormuz traffic returning to normal by year-end fell to 15.5% from 19.5%.
WTI crude jumped 6.7% to its highest settlement since May after Houthi forces took Mokha, but the barrel left its heaviest mark on the Fed bet rather than the oil patch: the September hike contract rose from 54% to 65% on a PPI report whose core undershot, nine of the 10-year yield's 12 basis points came from real yields, gold fell, the energy stock fund closed 0.58% lower, and the S&P 500 took its entire loss before the opening bell.
END
eli terminal • Thursday September 10, 2026