One-day moves, September 4
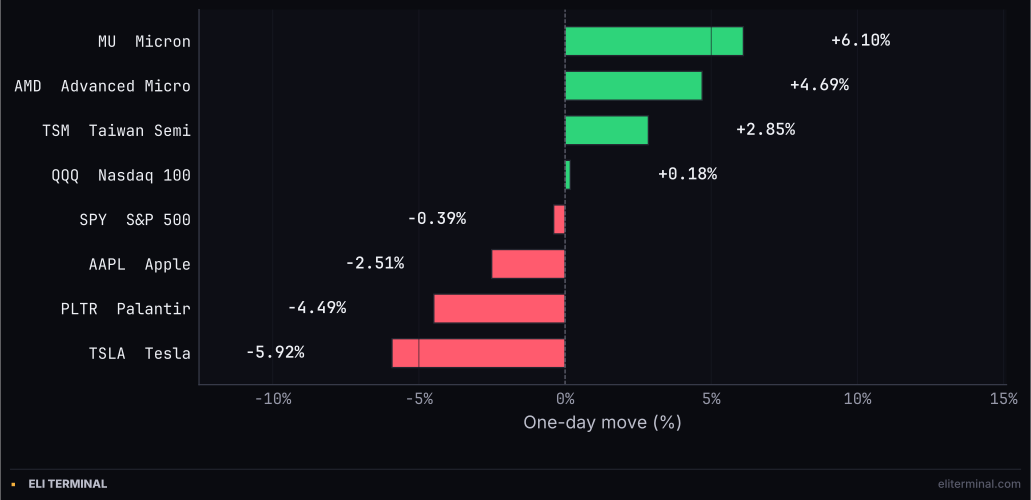
The chip and memory names rallied together. Tesla and Palantir fell together. The index sat in between, barely moving.
Micron rose 6.1% to a record close and Tesla fell 5.9% after its Cybercab debut, the same Friday a blowout August jobs report reversed the week's rate bet.
The chip and memory names rallied together. Tesla and Palantir fell together. The index sat in between, barely moving.
Nonfarm payrolls rose 162,000 in August against a consensus near 53,000, the Bureau of Labor Statistics reported at 12:30 UTC. The unemployment rate held at 4.1% and average hourly earnings rose 3.1% over the prior twelve months, with Leisure and Hospitality adding 62,000 of the total while Information and Financial Activities shrank.
Gold's 12:30 UTC candle opened at 4,520.90 and closed at 4,440.90 fifteen minutes later, a 1.8% drop inside the exact quarter hour the report crossed the wire. The 10-year yield's matching candle ran from 4.754% to 4.796%, a jump of more than 4 basis points in the same window. Both moves reversed a chunk of Thursday's action: gold had closed Thursday at 4,491.70 after climbing from 4,366.30 on Wednesday, and Friday's print erased more than half of that two-day gain by the close of 4,429.80.
The Kalshi contract on a 25-basis-point September hike traded at 43% at noon UTC Friday and 54% by 1pm UTC, an 11-point jump inside the hour containing the jobs number. The mirror-image Polymarket contract on no change in September fell from 59.5% to 48.5% in the same hour. Both markets gave back only a point or two into the 4pm close, holding most of the post-report move.
The reversal undid Thursday's swing almost exactly. The same Kalshi hike contract had fallen from 53% to 41% between noon and 2pm UTC Thursday, the hour containing that morning's international trade and jobless claims releases. Friday's jobs number pushed the contract back through Wednesday's level of roughly 55%, landing at 53% by the close, a full round trip in two sessions.
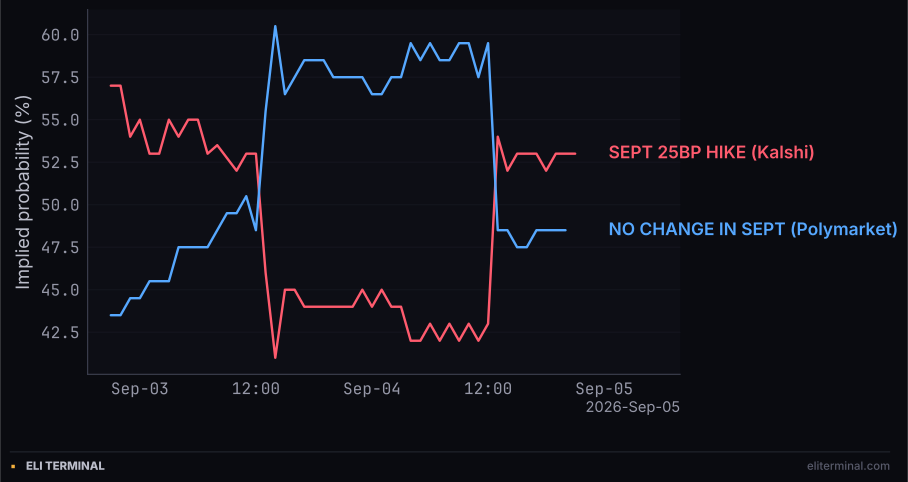
Two mirror-image contracts, two reversals, both landing inside the sixty minutes after a data release.
Kevin Warsh has chaired the Federal Reserve since his Senate confirmation in May, and the Federal Open Market Committee's next decision lands September 16. Friday's jobs beat gives hike bets more room to run into that date than they had a day earlier, though the market's own two-day round trip argues the pricing remains sensitive to the next data point rather than settled.
Tesla fell 5.9% to 354.08, its worst session since July 23, after Thursday night's Cybercab launch in Austin. The invitation-only event carried paying riders in a vehicle with no steering wheel and no pedals, but management left pricing, production cadence and the regulatory path unaddressed. Barclays wrote that the lack of direct communication was disappointing, with no fresh detail on growth or scaling targets.
The National Highway Traffic Safety Administration opened an audit Thursday into whether Tesla properly self-certified the Cybercab as compliant with federal motor vehicle safety standards. Tesla's premarket tape was already sliding before Friday's cash open, from 370.71 at 8am UTC down to 361.93 by 1pm UTC, then extending to 353.23 within the first hour of trading. Thursday's session, by contrast, had carried Tesla up 5.4% into the event itself.
Palantir fell 4.49% to 174.33 on Friday, one session after rising 7.71% on Thursday and two sessions after falling 5.81% on Wednesday. Wednesday's drop followed Google DeepMind's unveiling of Gemini 3.8 Flash Cyber, a government and cybersecurity model that investors read as encroaching on Palantir's core defense business. Thursday's rebound followed news of an expanded Palantir alliance with PwC.
No Friday-specific Palantir news turned up in a search of the day's wires. The stock's own hourly path shows it drifting down slightly overnight from Thursday's 182.53 close, then falling hard in the first trading hour, from 180.02 at 1:30pm UTC to 176.43 by 2:30pm UTC, and continuing to 174.91 by 3:30pm UTC. Three sessions, three moves near or above 4%, in three different directions.
Micron, Tesla and Palantir all posted their sharpest single-hour moves of the week in the 1:30pm UTC hour, the New York cash open, but in opposite directions. Micron's hourly candle ran from 971.06 to 1,000.11, a jump through the 1,000 level inside sixty minutes. Tesla's and Palantir's hourly candles in the same window fell 2.5% and 2.0% respectively.
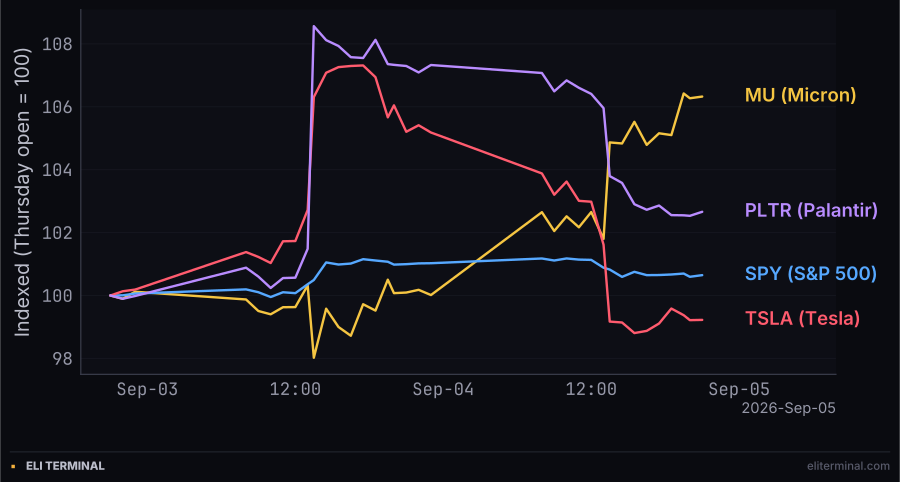
The index barely leaves its band. The three single names do almost all of the day's work, in both directions.
AMD and Taiwan Semiconductor moved with Micron rather than with Tesla or Palantir, closing up 4.69% and 2.85%. The S&P 500 held a band of roughly 773 to 771 for most of the session and closed down just 0.39%, a fraction of the swings inside any of the four single names carrying the day's real volatility.
Micron closed at 1,016.59, up 6.10% and above the 1,000 mark for the first time, with SanDisk and SK Hynix posting similar gains the same week. A search of Friday's wires found no Micron-specific news; the move sits alongside a broader memory sector re-rating built on tight DRAM and NAND supply that TrendForce and other trackers had already been flagging through August. That broader story explains the sector; it does not explain why Friday, specifically, produced the sharpest single-day jump of Micron's year to date.
WTI crude fell from 90.76 at 11:45am UTC to a session low of 89.02 by 2pm UTC, a decline that lines up with the same stronger-dollar, higher-yield move the jobs report drove through gold and rates. The dollar index closed the day up 0.16% at 99.16. From that 2pm low, oil climbed almost without interruption through the New York afternoon, breaking back above 91 by 6:15pm UTC and closing at 91.48, up 0.20% on the day despite the morning's macro headwind.
Iran launched missile and drone attacks on Kuwait on Wednesday, according to Kuwait's army, a day after Trump had said the renewed hostilities with Iran would not run much longer. Oil's afternoon climb has no single matching headline in Friday's wires; the recovery reads as a grind rather than a jump, consistent with a standing geopolitical risk premium reasserting itself once the dollar-driven selling faded rather than any new print crossing the tape that hour.
The Federal Open Market Committee's next rate decision is scheduled for September 16, twelve days after Friday's jobs beat pushed hike pricing back toward the middle of its recent range. Between now and then, the contracts that moved 11 points in an hour on Thursday and again on Friday give a sense of how much the pricing can still swing on a single data point.