Fed hike odds, stocks and long bonds, August 28
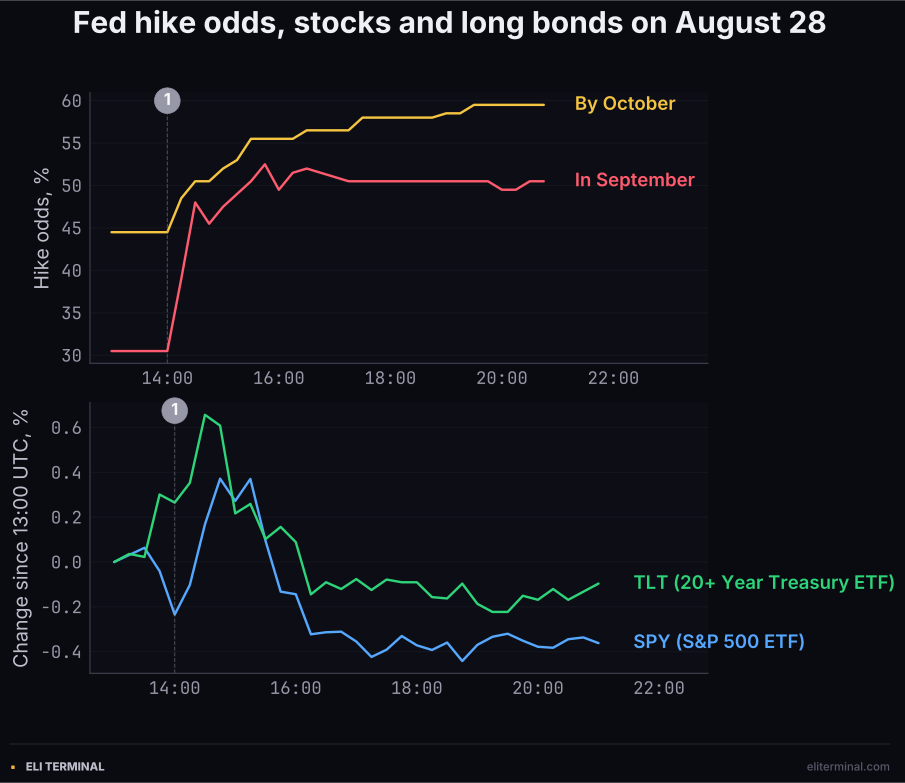
September's odds moved once, in the first half hour. The October contract kept climbing, and stocks and long bonds turned lower together after 15:00 UTC.
Fed Chair Kevin Warsh's Jackson Hole keynote turned a September rate hike into a coin flip inside 30 minutes, and the S&P 500 finished down only 0.25% after rallying with long bonds and then falling with them.
September's odds moved once, in the first half hour. The October contract kept climbing, and stocks and long bonds turned lower together after 15:00 UTC.
The Federal Reserve published Chair Kevin Warsh's first Jackson Hole keynote at 14:00 UTC, and the Polymarket contract on a September rate hike sat at 30.5% in the quarter hour before it. It read 39% at 14:15 UTC and 48% at 14:30 UTC, and closed the session at 50.5%. Kalshi's deeper September hike market finished at 49%, up from 30%.
"We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do," Warsh said in the speech text, which put 12-month PCE inflation at 3.7% and the six-month rate at 4.1%. He also said responsibility for 65 months of elevated inflation "sits squarely with the central bank."
The two-year Treasury yield closed at 4.34%, up 14 basis points and the highest since July 23. With the federal funds target at 3.50% to 3.75%, that leaves the two-year 59 basis points above the top of the range, a gap that prices tightening rather than a hold.
Warsh was not the only release at 14:00 UTC. The University of Michigan's final August survey cut year-ahead inflation expectations to 4.0% from a preliminary 4.3%, and the Bureau of Labor Statistics posted a preliminary benchmark revision of minus 79,000 jobs to March payrolls.
Gold futures dropped from 4,657.50 to 4,597.50 in the next ten minutes anyway, and the dollar index rose from 99.20 to 99.46. Of the three releases, only the speech pointed toward tighter policy, and every rate-sensitive price traded as if the other two had not printed.
On Thursday, Cleveland Fed President Beth Hammack said "now is the time to act," and Kansas City Fed President Jeffrey Schmid questioned what current policy was restricting at all, according to an investingLive recap. Kalshi's September hold contract rose that session, from 67% to 70%.
Friday's 21-point drop in the same contract came from the chair alone, in a speech that also argued forward guidance "has overstayed its welcome." Warsh promised nothing about September, and the market marked a hike at even money within the half hour.
For the first 55 minutes, stocks traded the keynote as good news. The S&P 500 ETF climbed to 774.96 at 14:55 UTC, up 0.50% on the day, while the 30-year yield eased from 5.18% at 13:50 UTC to 5.16% at 14:35 UTC and the 20-plus year Treasury ETF rose 0.66% from its 13:00 UTC level. Two-year yields rising while long yields fell made it a textbook bear flattener.
The long end did not hold that view. By 18:35 UTC the 30-year yield was back at 5.21%, the long-bond ETF had erased its gain to close down 0.30%, and the S&P 500 ETF slid across the same window to settle at 769.35, 0.72% below its high. Two-year note futures barely retraced their 14:00 UTC drop and ended the day at their lows.
September's hike contract spent the rest of the day between 45.5% and 52.5%. The Polymarket contract that pays on a hike by the October meeting kept rising instead, from 50.5% at 14:45 UTC to 59.5% by 19:30 UTC, and Kalshi's thin December hike market went from 34.5% before the speech to 51% by 20:00 UTC.
That second leg carried no headline. No Fed remark, data release or policy news surfaced between 15:00 and 16:30 UTC, the window in which the 10-year yield rose from 4.67% to 4.73% and the S&P 500 ETF gave back its rally; the pricing simply moved from one hike toward more than one.
Gold futures traded at 4,657.50 at 13:55 UTC, up 1% on the day. They fell 1.3% in the first ten minutes after the speech, recovered to 4,633 at 15:00 UTC while long bonds were rallying, then slid with them to close at 4,478.10, down 2.85% and the lowest close since August 18.
The same two steps took silver down 3.51%, after it had traded 3% higher before the keynote, and bitcoin down 3.02% to 77,830, one day after a three-month closing high of 80,257. All three took their larger loss after 15:00 UTC, in the window with no news, not in the minutes after the speech.
WTI crude went the other way across the same afternoon, rising about 1% between 13:00 and 17:00 UTC before settling at 83.40, down 0.16%, as traders weighed rumors of a shipping deal through the Strait of Hormuz. The dollar's 0.54% gain and the rate repricing landed on the metals and left the barrel alone.
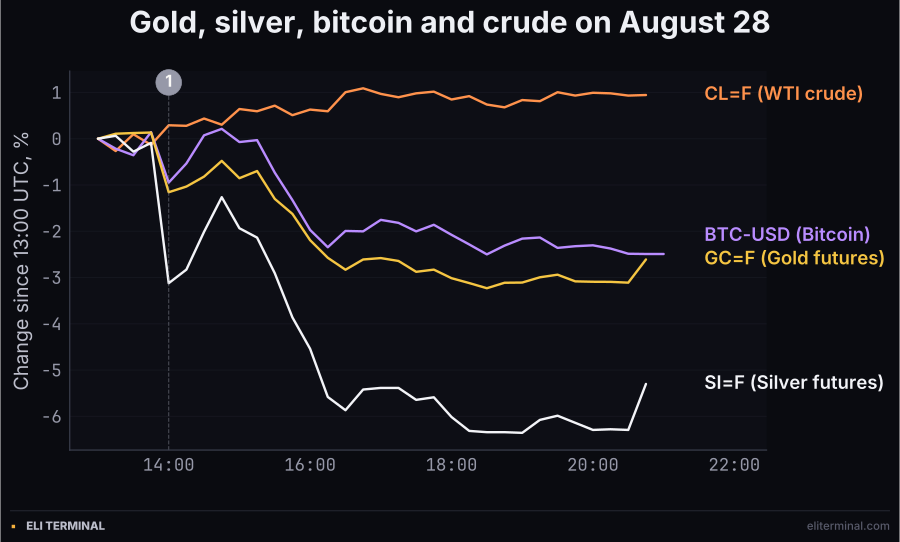
The metals and bitcoin fell twice, at 14:00 UTC and again after 15:00 UTC. Crude climbed through both.
Small caps took the repricing most directly. The Russell 2000 fell 1.39% to 2,972.37, its weakest close since July 31, and its ETF dropped 0.52% in the ten minutes after 14:00 UTC, against 0.19% for the S&P 500 ETF.
The utilities ETF, the sector most often traded as a bond substitute, fell 1.04% to its lowest close in six months, while the five-year Treasury yield closed at 4.48%, its highest over the same stretch. The VIX closed down 0.55% at 14.43: equity options priced no more index risk after the speech than before it.
Nvidia closed at 217.55, down 4.57%, giving back 57% of Thursday's 8.7% jump on current-quarter guidance of 108 billion dollars. Its slide began before Warsh spoke, from 228.62 at 13:00 UTC to 225.26 at 13:55 UTC, and continued to 217 through the headline-free afternoon.
Marvell's Thursday-evening results raised its revenue targets to 12 billion dollars for fiscal 2027 and 18 billion for fiscal 2028. Chief executive Matt Murphy said the Google custom-chip deal would "contribute much more significantly in fiscal year 2029," BNN Bloomberg reported, and the stock closed down 10.28% at 216.62.
In one session, the semiconductor ETF wiped out all of Thursday's 3.10% Nvidia-earnings rally, losing 3.47% to 553.11 and closing below Wednesday's level.
Amazon committed on Wednesday evening to deploy 2 million more Nvidia GPUs in 2027 and 2028. Two sessions later the buyer rose 3.97% to 266.43 and the seller fell 4.57%, a spread of more than 8.5 points on opposite ends of the same order.
Most of Amazon's gain arrived after the keynote, from 259.50 at 14:00 UTC to 266.85 at 15:15 UTC, on a day Evercore ISI raised its price target to 355 from 315. Unlike the index, it held the move into the close.
Alongside it, Microsoft rose 1.68% to 513.53, its fifth straight gain and highest close in six months, while Alphabet added 1.74% and Apple 1.63%. The Nasdaq's 0.52% loss was the net of those gains against a chip complex down more than 3%.
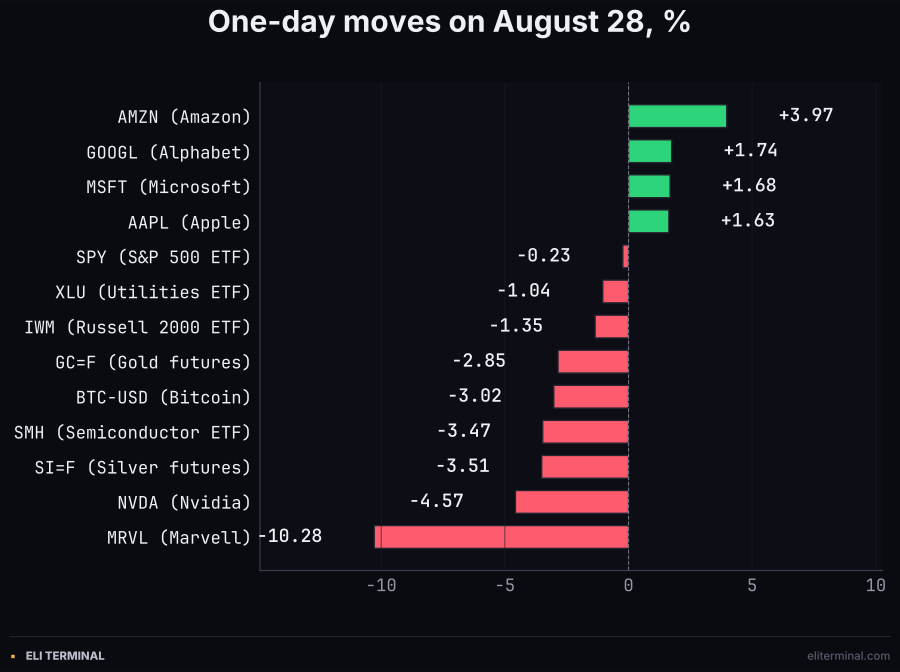
Platforms up; chips, metals, small caps and utilities down. The S&P 500's 0.23% hides a 14-point spread between Amazon and Marvell.
One speech undid the whole jobs-driven move in Kalshi's September hold contract, which closed at 49% from 70% on Thursday. It last closed that low on August 6, the day before July's payroll report lifted it to 64% in a single session.
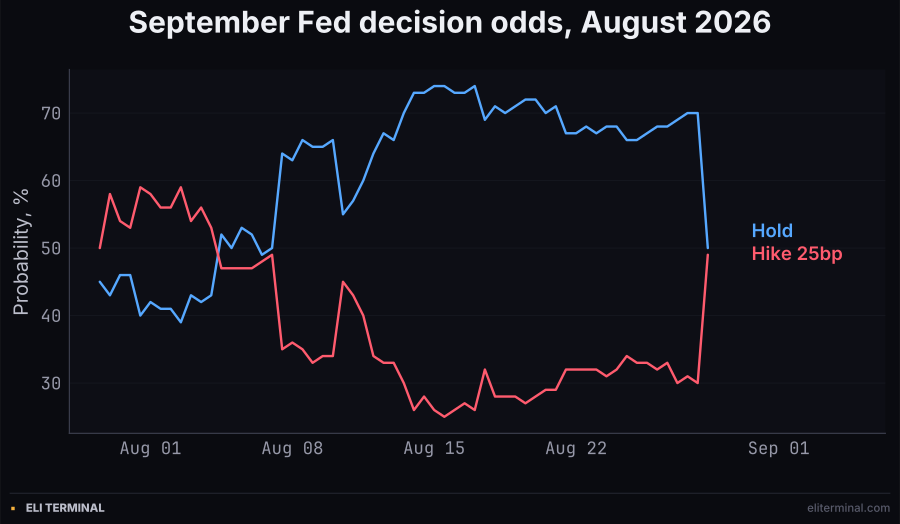
The hold contract spent three weeks near 70%. One keynote brought it back to where it stood in the first week of August.
ISM manufacturing and JOLTS job openings print at 14:00 UTC on September 1, ADP private payrolls on September 2, and the August employment report at 12:30 UTC on September 4, the last payroll figure before the Federal Open Market Committee announces its decision at 18:00 UTC on September 16.
Warsh set the bar at underlying inflation moving to target "clearly and at sufficient speed," with the six-month PCE rate at 4.1%. A firm August payroll number removes the labor market as an argument against a hike; a soft one has to be soft enough to outweigh that inflation rate.