Meta, Alphabet, and the S&P, August 25–26
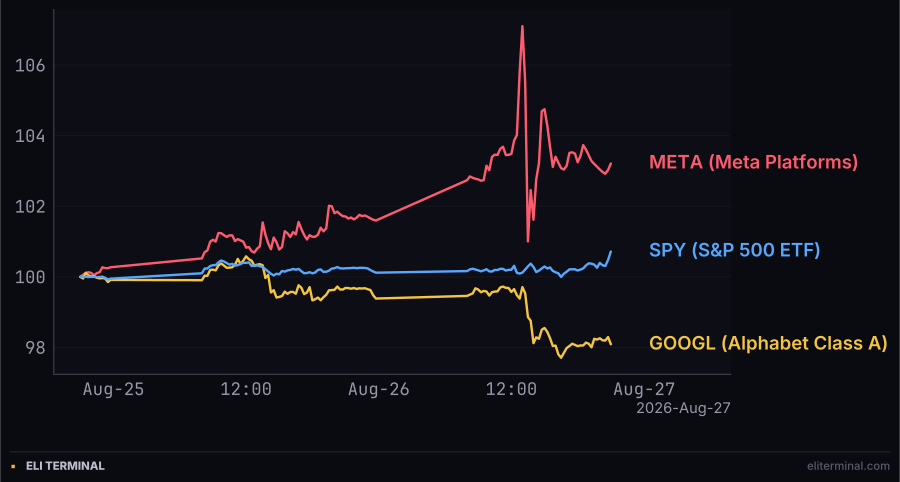
Meta ran 36 points in under an hour and gave most of it back. The index it trades inside never moved.
Meta round-tripped a 36-point range on a $17.1 billion settlement, Alphabet fell 1.43% for no published reason, and the S&P closed exactly flat, waiting on Nvidia.
Meta ran 36 points in under an hour and gave most of it back. The index it trades inside never moved.
The S&P 500 fund SPY closed at 766.08, up 0.02%. The Nasdaq-100 fund QQQ added 0.09% to 711.37. The Russell 2000 fund IWM slipped 0.10% to 298.93, and the Dow fund DIA fell 0.19% to 534.23, the largest move of the four.
None of it moved more than two-tenths of one percentage point in either direction. A market genuinely reacting to that morning's inflation data, or bracing for three earnings reports due after the bell, does not usually look like this.
Core PCE, the Fed's preferred inflation gauge, held at 3.3% year over year in July, unchanged from June and in line with forecasts. Headline PCE ran at 3.7%, a touch hotter than consensus. Both crossed the wire at 8:30 a.m. Eastern alongside the second estimate of second-quarter GDP.
That GDP estimate held growth at 1.5% annualized, unchanged from the advance reading, but revised consumer spending up to a 3.4% annualized pace. The same report's fresher number, inflation-adjusted personal spending for July itself, was flat month over month, a sharp slowdown from June's 0.4% gain, even as personal income rose 0.4%.
One line in the release said the consumer had been stronger than first measured through June. The next line said the consumer stalled in July. SPY's 15-minute bar spanning 8:30 a.m. Eastern moved from 766.42 to 764.90 and the index finished the day almost exactly where that bar started.
A Kalshi contract on whether the Federal Reserve simply holds rates at its September meeting priced a 66% chance the morning of the PCE release and a 66% chance after it. A separate Polymarket contract on a September hike ticked down a point, to 33.5% from 34.5%, the opposite direction a hotter headline number might imply.
That hold-odds contract had already run from 52% on August 6 to as high as 73% in mid-August before drifting back to 66% the week of the print. Wednesday's data landed inside that drift without adding to it.
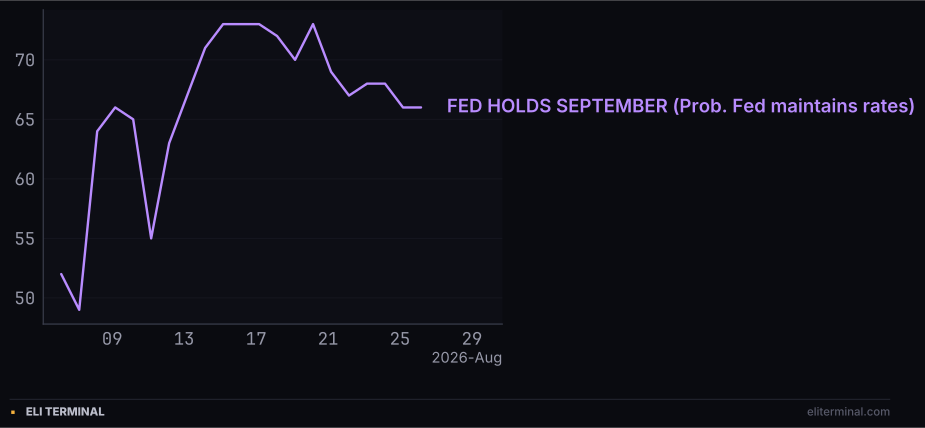
66% before the inflation data. 66% after it.
Meta closed Tuesday at 570.05. In the 45 minutes before Wednesday's opening bell it ran from about 581 to an intraday high of 598.44, a premarket gain of better than 5%. It opened the regular session at 590.44 and fell to 561.94 within that same 15-minute bar, a round trip of roughly 36 points before 9:45 a.m. Eastern.
The stock climbed back through the morning to a session high of 588.76 by 11:00 a.m. Eastern, faded through the afternoon, and closed at 576.14, up 1.07% on the day. The S&P 500 fund traded in about a half-point range across the same stretch.
State attorneys general and Meta reached a $17.1 billion settlement Wednesday resolving claims from 47 states and the District of Columbia that Instagram and Facebook are addictive and unsafe for children. Meta agreed to cap teen use of both apps at two hours a day and to mute notifications during school hours and overnight.
Meta pays $12.7 billion of that total regardless of what anyone else does. It owes the remaining $5.3 billion only if TikTok and YouTube adopt matching one-hour daily limits for young users and each contribute a comparable sum of their own. The premarket rally treated the number as a resolution. The sell-off at the open treated the terms as a new cost.
Alphabet opened Wednesday at 346.62 and slid steadily to 341.71 by 10:15 a.m. Eastern, 45 minutes of grinding decline rather than a single break, before spending the rest of the session between 340 and 343. It closed at 342.00, down 1.43%, near its low of the day.
A sweep of Wednesday's wires found no Alphabet-specific news. YouTube is one of the two platforms named in Meta's settlement as a condition of Meta's full payout, which puts Alphabet adjacent to the day's biggest story with no reporting connecting the two. The timing is documented. The cause is not.
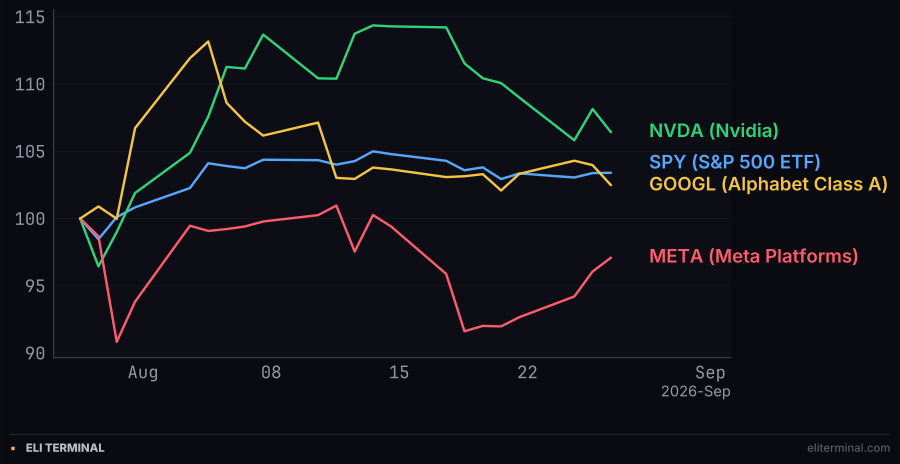
Zoomed out, Wednesday's stillness in the index is the rule. The swings in Nvidia and Meta are, too.
Nvidia fell 1.59% to 209.66 during the regular session, trading as low as 210.78 in the first fifteen minutes, ahead of a report due after the bell. At 4:36 p.m. Eastern, twenty-four minutes before this report's close, Nvidia filed its results: $96.2 billion in quarterly revenue, up 106% from a year earlier, and non-GAAP earnings of $2.22 a share.
Nvidia guided third-quarter revenue to $108 billion, above the roughly $104.2 billion analysts had modeled, and Jensen Huang forecast about 70% revenue growth for fiscal 2028. The company also flagged gross margin sliding toward 71% to 72% by its fourth fiscal quarter, tied partly to memory costs, after purchase commitments for memory more than doubled to $279 billion from $119 billion the prior quarter. None of it had traded yet by the time this report closed.
CrowdStrike filed its results at 4:07 p.m. Eastern: $1.47 billion in quarterly revenue against a $1.44 billion estimate, adjusted earnings of 31 cents a share against 29 cents expected, and a raised full-year revenue outlook of $5.99 billion to $6.01 billion. CrowdStrike lifted its net-new annual recurring revenue growth guidance by more than 600 basis points, to a 34% midpoint.
Salesforce filed four minutes earlier, at 4:03 p.m. Eastern: $11.35 billion in quarterly revenue against $11.32 billion expected, with net income up 87% to $3.53 billion, boosted by a $2.6 billion gain on its stake in Anthropic. Annualized revenue from its Agentforce AI products topped $1.5 billion, up 240% from a year earlier, and Salesforce raised its full-year revenue guidance by $200 million.
All three filings crossed the wire in the same 33-minute window, 4:03 to 4:36 p.m. Eastern. None of the three stocks had a chance to trade on the news before the close this report is built on.
Weekly jobless claims are due at 8:30 a.m. Eastern Thursday, alongside earnings from Marvell Technology and three Canadian banks: Royal Bank of Canada, Toronto-Dominion, and CIBC. None of that competes with the real test: whether Nvidia, CrowdStrike, and Salesforce open Thursday trading anywhere near where they closed Wednesday.
Nvidia has fallen after each of its last four earnings beats despite topping estimates every time. Wednesday's guide, its margin warning, and Huang's growth forecast are the inputs on the table. Thursday's open is the first vote.