Monday August 17, 2026 • The Iran Deadline Lapses and the Long Bond Breaks Out
30-Year Treasury Yield Hits 5.31%, Brent Tops 90, Microsoft Falls 3%
The long bond closed at 5.31%, its highest since 2007, and made its decisive climb in the same hour crude jumped on Iran, while Microsoft fell 3.04% and Micron rose on a separate, earlier clock.
Monday 4pm close
SPY 772.67 −0.47%
·
QQQ 729.87 −0.16%
·
IWM 304.06 −0.34%
·
VIX 15.19 +6.60%
Treasuries and credit, vs Friday
30Y 5.309% +4.4bp
·
10Y 4.724% +2.8bp
·
5Y 4.376% +1.4bp
·
TLT 81.35 −0.84%
·
LQD 105.70 −0.40%
Crude, settle
WTI 84.50 +2.55%
·
BRENT 90.87 +2.65%
·
XLE 62.58 +1.08%
AI spenders and suppliers
MSFT 480.35 −3.04%
·
META 568.97 −3.54%
·
ORCL 146.65 −2.57%
·
MU 1,011.75 +4.13%
·
SNDK 1,786.85 +8.88%
Odds, Friday to Monday close
SEPT FED HIKE 32% +6 pts
·
HORMUZ NORMAL BY DEC 31 36.5% −9 pts
The 30-year Treasury yield, Monday, five-minute bars
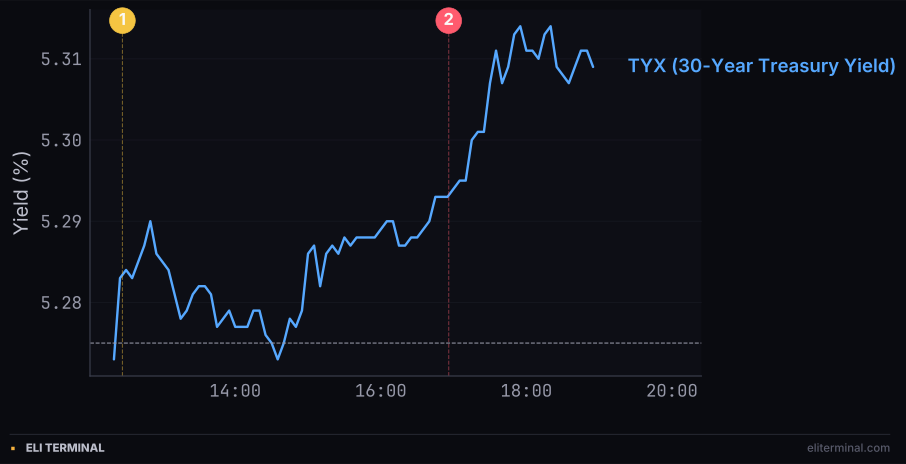
Marker 1: Reuters reports Iran's shift to a fully offensive posture. Marker 2: drone strikes reported in Iraqi Kurdistan, the start of the oil leg. Dashed line: the 5.275% close of July 31.
The 30-year yield broke its July high while the 10-year stayed below its own
The 30-year Treasury yield closed Monday at 5.309%, up 4.4 basis points and past the 5.275% close of July 31 that had marked the top of this run, the highest for the long bond since 2007, according to Bloomberg. The 10-year finished at 4.724%, still two basis points under its own July 31 close. Only the far end of the curve set a new high.
Each longer maturity rose more than the one before it: the 13-week bill yield added 0.6 basis points, the 5-year 1.4, the 10-year 2.8 and the 30-year 4.4, with the 2-year up about 2. Ten-year breakeven inflation, the slice of yield that pays for expected inflation, rose a single basis point on a day crude gained more than 2.5%. The added long-end yield was mostly not a bet on inflation.
Over the past month the 30-year has climbed 24 basis points and the 5-year 10. Monday was not the start of the steepening; it was the day the steepening cleared the prior peak.
Five-, ten- and thirty-year Treasury yields, three months
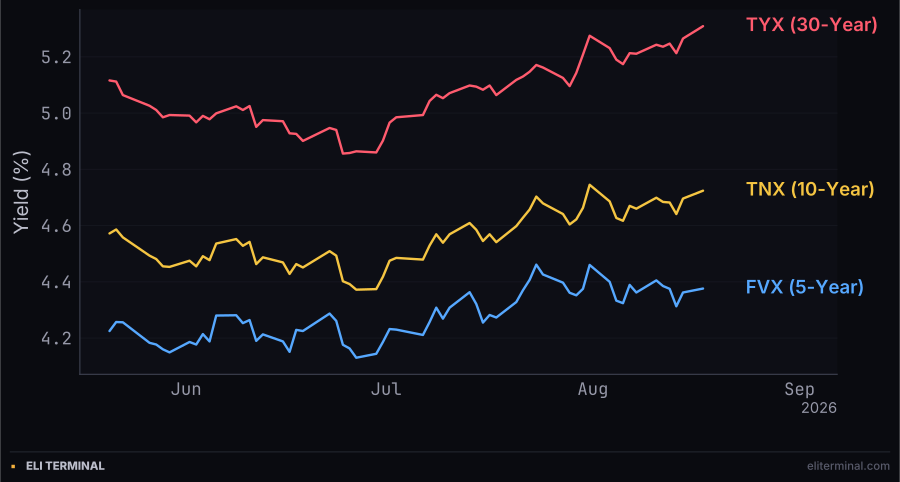
The 30-year closed at a new high on Monday. The 10-year and 5-year did not.
Iran's offensive-posture report moved crude and the long bond inside five minutes, then both gave it back
President Trump's Fox News interview, in which he said Iran should "put up the white flag of surrender" and threatened to bomb Oman if it "gets in the way" in the Strait of Hormuz, was circulating by 11:31 UTC (Al Jazeera). West Texas crude drifted from 82.49 to 82.29 over the next forty minutes.
Just before 12:30 UTC, a senior Iranian official told Reuters that Tehran had moved from a defensive to a "fully offensive" posture and would attack to break the U.S. naval blockade if the June memorandum was not implemented within weeks (Reuters via Insurance Journal). In the 12:25 UTC five-minute bar, WTI went from 82.42 to 82.82 and the 30-year yield from 5.273% to 5.283%. A threat against an American ally had moved nothing an hour earlier; a threat against the blockade itself moved both markets at once.
The New York Fed's Empire State manufacturing index came in at 20.6 against a forecast of 11 at 12:30 UTC, its strongest since late 2021 (New York Fed), and the long bond added under a basis point in the twenty minutes after. By 14:35 UTC the 30-year was back at 5.273%, a fraction below the July 31 close, and WTI touched 82.17 at 14:55. Nothing was left of the morning's Iran move.
The afternoon oil leg carried the 30-year yield to its high of the day
WTI traded 82.85 at 16:55 UTC and 84.79 an hour later, up 2.3%, and Brent went through 91 for the first time Monday. Over the same stretch the 30-year yield rose from 5.293% to 5.314% by 18:20 UTC, the S&P 500 ETF slipped from 774.68 to 773.41, and the VIX printed its session high of 15.46 in the 17:15 quarter hour.
No oil-specific headline surfaced inside that hour. The nearest timestamp is a CBS News post at 12:56 p.m. ET, 16:56 UTC, reporting two drone strikes on the office of Kurdistan Region Prime Minister Masrour Barzani, reportedly launched from near the Iranian border (CBS News), and crude's climb began in the next five-minute bar. The sequence is adjacent; a cause is not established.
Physical traffic was already close to nothing. Kpler counted three vessels crossing Hormuz on Sunday, against roughly 130 a day before the war began on February 28 (CNBC). Brent settled at 90.87 and WTI at 84.50.
WTI crude and the S&P 500 ETF, Monday, five-minute bars
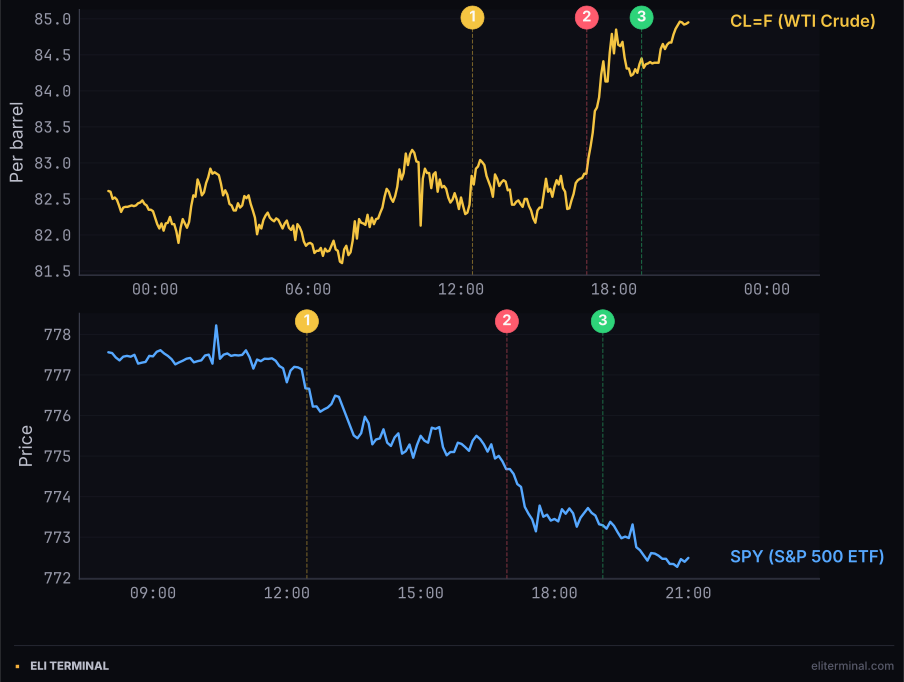
Marker 1: Reuters Iran report. Marker 2: Kurdistan drone strike report. Marker 3: Nvidia's Ohio financing announcement.
The September Fed rate-hike bet climbed after the oil hour, not before it
Kalshi's contract on a 25 basis point hike at the September meeting stood at 26% on Friday and 24% at 13:00 UTC Monday. It read 25% at 17:00 as crude started to run, then 27%, 29%, 30%, and 32% by 21:00. The bet on Fed policy trailed the long bond by hours rather than leading it, and the 2-year yield's gain of about 2 basis points was less than half the 30-year's.
On Polymarket, the contract on Hormuz traffic returning to normal by December 31 held at 42.5% through 18:30 UTC and fell to 38.5% in the 18:45 quarter hour, just after Trump told reporters at 2:42 p.m. ET that the U.S. could handle Oman "very easily" (CBS News). It finished at 36.5%, from 45.5% on Friday. The market on a U.S. invasion of Iran before 2027 spent the whole session between 16.5% and 17.5%, so the odds moved toward a longer blockade, not a wider war.
Microsoft, Meta and Oracle broke at the opening bell, hours before the bond's afternoon leg
Microsoft opened near 491.50 and traded 485.84 by 13:40 UTC, ten minutes into the session. Meta's first regular-hours five-minute bar closed at 579.23, 1.8% under Friday, and Oracle reached 146.27 by 13:40. All three slid into the afternoon: Microsoft closed at 480.35, down 3.04%, Meta at 568.97, down 3.54%, and Oracle at 146.65, down 2.57%.
Each had a morning input of its own. A Morgan Stanley note argued that some hyperscalers do not generate enough free cash flow to cover their outlays and will need more loans at higher rates, with Microsoft set to spend 190 billion dollars this year (Motley Fool). Meta faced a 29-state lawsuit over harm to young users, led by California Attorney General Rob Bonta, with oral arguments set to begin the next day (Motley Fool). The selling hit at 13:30 UTC; the 30-year's biggest leg came at 17:00.
Microsoft still sits 22% above its level of a month ago, most of it from the July 30 post-earnings jump. Monday took back roughly a seventh of that gain.
Micron crossed 1,000 as the memory makers rose against the companies paying for the buildout
Micron traded above 1,000 before the bell, reached 1,033.35 in the 15:00 UTC quarter hour, then faded to close at 1,011.75, up 4.13%. Sandisk rose 8.88% and Western Digital 5.35%, and the iShares Semiconductor ETF gained 1.58%. Memory suppliers and the platforms buying their output went opposite ways from the same opening bar.
The stated inputs were Elon Musk's Friday post calling memory the binding constraint on AI, Sandisk's August 13 investor day and a New Street upgrade of Micron to Buy with a 1,250 target (24/7 Wall St.). The line between spenders and suppliers was not clean. Amazon and Alphabet, both heavy AI borrowers, fell only 0.51% and 0.55%, and Nvidia finished flat.
AI spenders and suppliers, one-day moves, August 17
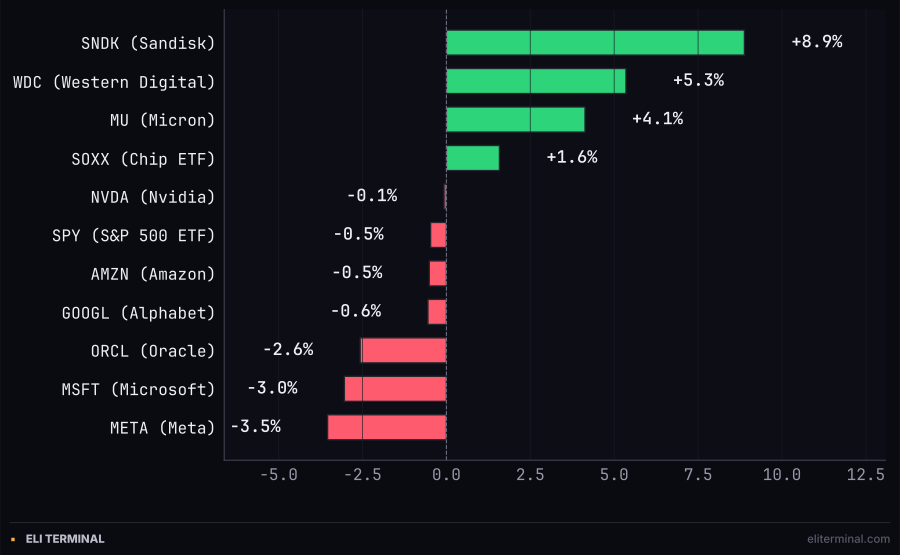
Memory makers up, the biggest platform spenders down, and the index in between.
U.S. high-grade bond sales set an August record the same day the long bond broke out
High-grade corporate issuance for August reached 145.2 billion dollars on Monday, passing the 136 billion of August 2020 for the month's record, with AI spending driving the year's pace (Bloomberg). The iShares investment-grade corporate bond ETF closed at 105.70, down 0.40% and at its lowest close in a year, while the high-yield ETF fell only 0.13%.
The ICE BofA investment-grade spread widened by one basis point, to 81. Long-dated corporate paper lost ground because the Treasury yield underneath it rose, not because credit risk was repriced, which is why the longer-duration high-grade fund fell three times as much as junk.
Nvidia backed 105 billion dollars of OpenAI data-center financing and its stock did not move
Shortly after 19:00 UTC, Nvidia said it would back up to 105 billion dollars of financing for SB Energy's PORTS-Pike campus in Ohio, which OpenAI will lease for 20 years and run exclusively on Nvidia hardware (CNBC). Nvidia traded 225.52 at 19:05 UTC and 225.89 at 19:35, then closed at 225.01, down 0.07%.
A chipmaker standing behind its customer's financing, on the day long-term money cost the most since 2007, drew no price response in either direction. The stock traded it neither as demand locked in nor as risk moved onto Nvidia's balance sheet.
Housing starts, a 20-year auction and the Fed minutes test the long end next
July housing starts print at 12:30 UTC Tuesday, the same day Home Depot reports; the homebuilder ETF fell 0.76% Monday even as builder sentiment edged up to 35. Treasury sells 16 billion dollars of 20-year bonds at 17:00 UTC Wednesday, a maturity the when-issued market priced near 5.27% on Friday, the highest since it returned in 2020 (Bloomberg).
Minutes of the July 28-29 FOMC meeting, where Lorie Logan, Beth Hammack and Neel Kashkari dissented in favor of a hike, follow at 18:00 UTC Wednesday. A tail at the auction would point to supply setting the long rate; hawkish minutes would hand the lead back to the front end.
The 30-year Treasury yield closed at 5.309%, its highest since 2007, and its decisive 2.1 basis point leg came between 16:55 and 18:20 UTC, the stretch in which crude rose 2.3% on Iran headlines, while breakevens barely moved, the September hike bet caught up only hours later, and Microsoft's 3.04% drop and Micron's 4.13% gain had already been set at the opening bell.
END
eli terminal • Monday August 17, 2026