One-day moves, August 13
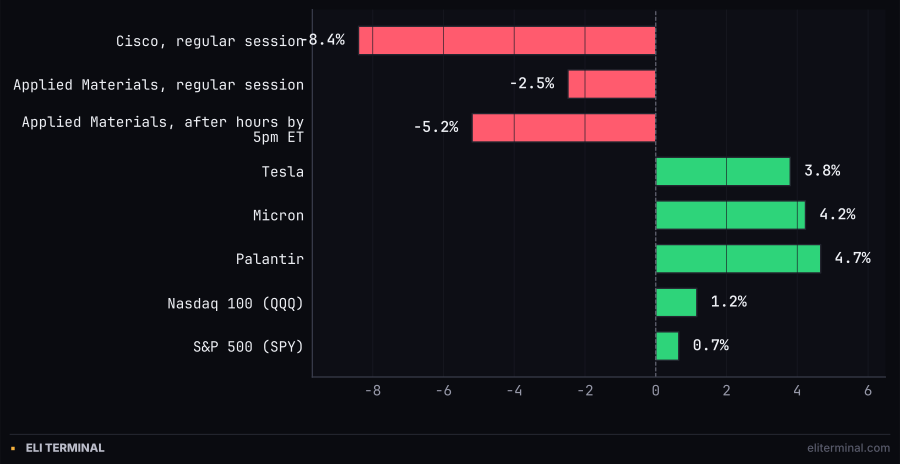
Two record quarters, two sessions of selling, and a record index close sitting in between.
Cisco fell 8.4% and Applied Materials gave back an intraday gain to close down 2.5%, both on record quarterly numbers, while the S&P 500 closed at 7,798.99, a fresh high.
Two record quarters, two sessions of selling, and a record index close sitting in between.
The S&P 500 closed at a record 7,798.99 Thursday, up 0.65%, after clearing 7,800 intraday for the first time. The Nasdaq Composite added 0.81% to 26,803.03 and the Dow rose 0.13% to 53,839.99. None of the three indexes closed near their low of the day.
Underneath that headline, two of the day's biggest single-name stories were the opposite of a rally. Cisco closed at 113.47, down 8.40%, and Applied Materials gave back a morning gain of more than 2% to close at 534.54, down 2.48%, before falling another 5.2% in the hour after its own earnings call. Both companies beat Wall Street on revenue and profit. The market sold both anyway.
Cisco's fourth-quarter revenue came in at 17.3 billion dollars, up 18% year over year, with non-GAAP earnings per share of 1.22 dollars against a Street estimate of 1.17. Total product orders rose 35% and hyperscaler AI infrastructure orders reached 4 billion dollars for the quarter, 9.3 billion for the fiscal year, with Cisco guiding to 7.5 billion dollars of AI infrastructure revenue in fiscal 2027. The release, filed after Wednesday's close, called it "another record year."
Non-GAAP gross margin fell to 66.3% from 68.4% a year earlier, even as the GAAP gross margin figure rose to 64.1% from 63.2%. That split, a GAAP margin gain against a non-GAAP margin drop, is the detail Thursday's coverage fixed on. The stock had already gapped down premarket and spent the session grinding from a morning high near 116 down to a low of 111.48 before closing at 113.47.
Applied Materials reported record revenue of 9.115 billion dollars, up 25% year over year, with GAAP earnings per share of 3.17 dollars, up 43%, and non-GAAP EPS of 3.50 dollars, a record. GAAP gross margin rose to 50.3% from 48.8%, the company's thirteenth consecutive quarter of year-over-year gross margin expansion. Applied guided fourth-quarter revenue to 10.25 billion dollars, above the roughly 9.55 billion analysts had modeled, and non-GAAP EPS to 4.02 dollars.
None of that showed up in the close. Applied ran from an opening print near 549 up to an intraday high of 563.76 by early afternoon, then reversed through the final ninety minutes of the session to finish at 534.54, down 2.48% on the day, ahead of its 4:30pm ET earnings call. In the hour that followed, the stock traded as low as 501.66 and stood near 506.80 by 5pm ET, down roughly 5.2% from the regular close and about 7.5% below Wednesday's 548.15.
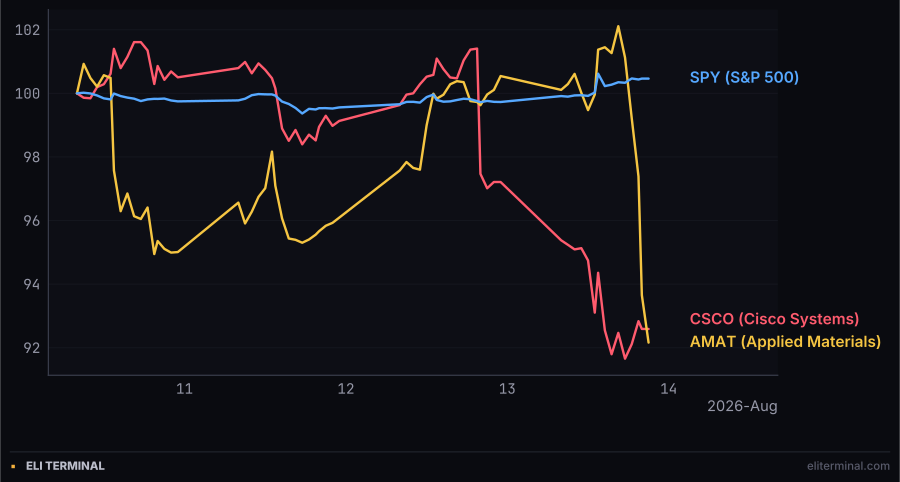
Both lines end the window below where they started. The market's line barely moves at all.
The producer price index for July came in flat month over month, below the 0.2% consensus, with core PPI up 0.2% against a 0.3% forecast, a second straight soft inflation reading after Tuesday's consumer price index. The same 8:30am ET release carried initial jobless claims of 209,000, above the 202,000 forecast and up from the prior week, a miss in the opposite direction that most coverage of the morning left out.
The 10-year yield was at 4.674% heading into the print and fell to 4.613% within the next twenty minutes, before settling at 4.641% by the close, down 4.1 basis points on the day. A Kalshi market on whether the Federal Reserve holds rates steady at its September meeting moved from roughly 66-68% before the release to 70-71% in the same hour and held there into the close. The bond market and that market both read the soft inflation number as the one that mattered.
West Texas crude opened Thursday near 82.70, fell to a session low of 80.09 by 10:00am ET, then jumped to 82.73 by 11:00am ET, a move of roughly 3.3% in a single hour with no headline found to explain it. From there it rolled over through the afternoon to close at 81.25, down 2.43%, with Brent down 2.15% to 87.07. Both benchmarks had traded near six-week highs earlier in the week on fears that attacks on shipping would keep the Strait of Hormuz closed to negotiation.
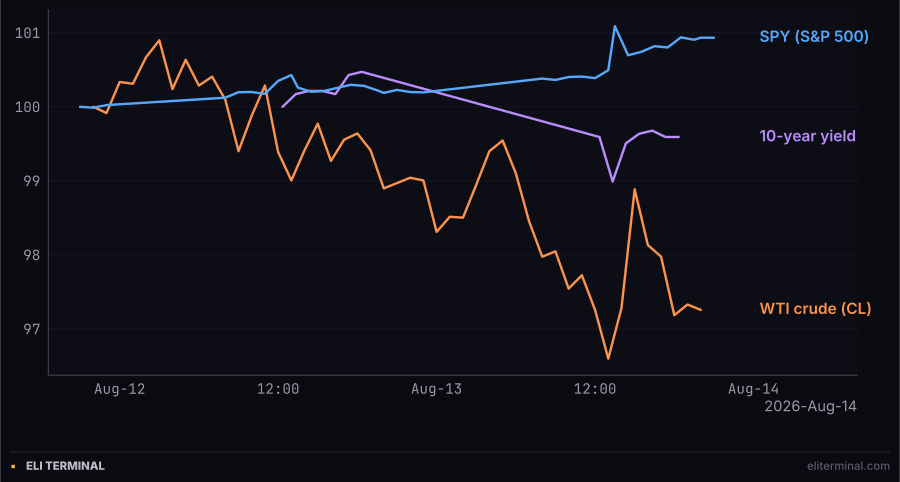
Crude's round trip and the yield's one clean drop happened inside the same day. Neither explains the other.
Palantir rose 4.66% to 179.01, Micron gained 4.23% to 949.83, Tesla added 3.80% to 339.96, Super Micro rose 4.12%, and Meta gained 2.78% to 594.97. None of the five had a same-day headline attached to it in a saturated search of Thursday's wires. The moves were real and large; the causes, if there were any beyond continued momentum in stocks already up sharply this year, did not print.
The energy sector ETF closed at 61.06, up 0.05%, flat on a day crude fell 2.4%. A sector that tracks its own commodity closely on most days simply didn't Thursday, one more piece of a session where the relationships investors expect to hold quietly didn't.
Advance retail sales for July print at 8:30am ET Friday, the next scheduled read on whether Thursday's soft-inflation, weak-claims mix reflects a slowing consumer or just a wholesale-price fluke. Applied Materials' stock, still finding a level in after-hours trading as this report was filed, will open Friday's session with a full day to react to Thursday's call in a way it didn't get to Thursday night.