One-day moves, August 12
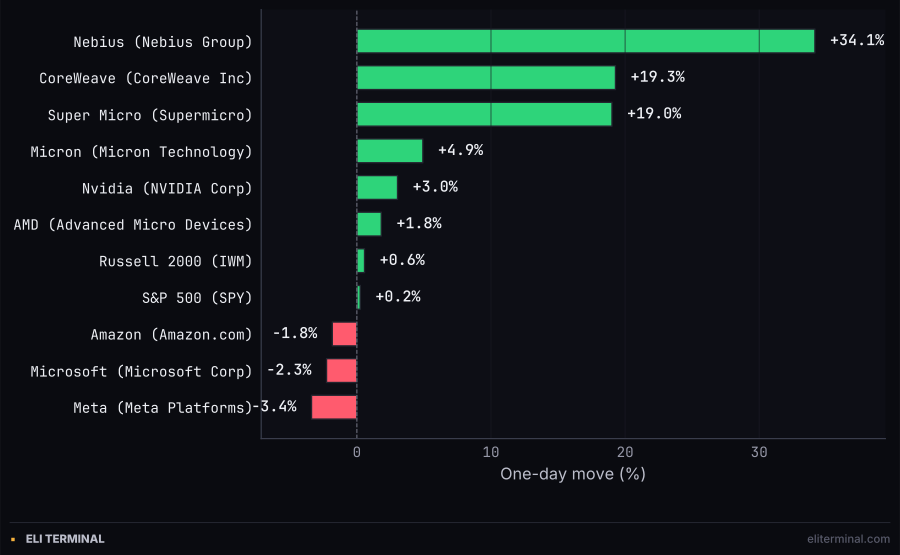
Three earnings beats did almost all of the day's work. The broader index barely moved.
Super Micro surged 19.0% and Nebius soared 34.2% on blowout earnings, while Meta Platforms fell 3.4% for no reason anyone published and the broader market barely moved on a tame CPI print.
Three earnings beats did almost all of the day's work. The broader index barely moved.
259.20 is where Nebius closed Wednesday, up 34.2%, after its cloud division reported revenue up 514% year over year to 575 million for the quarter. CoreWeave closed at 107.73, up 19.3%, on revenue that roughly doubled year over year and a raised full-year outlook near a 12.8 billion midpoint. Super Micro closed at 37.61, up 19.0%, after fiscal fourth-quarter non-GAAP earnings of 1.70 a share cleared a Wall Street range that topped out at 96 cents.
All three closed at their highest level of the past month, and by a wide margin. Nebius had not traded above 225.74 at any point since July 14; Wednesday's close cleared that by more than 33 points. CoreWeave's prior one-month high was 91.90; Super Micro's was 31.69. None of the three had come within striking distance of Wednesday's level before their numbers landed.
Super Micro's results moved the stock before Wednesday's cash session even opened, lifting it from Tuesday's 31.60 close to above 34 in premarket trading. At the 13:30 UTC open the stock ran from 34.99 to an intraday high of 37.13, fell back to 33.94, and recovered to 36.84, a swing of roughly nine points on the day's high-low range packed into the first fifteen minutes of trading. It spent the rest of the session grinding higher into a 37.61 close.
More than half of Super Micro's calendar-month gain arrived in this single session. The stock closed July 14 at 27.65 and Tuesday at 31.60; Wednesday's move alone added more percentage points than the three prior weeks combined.
Micron closed at 911.29, up 4.9%. Nvidia added 3.0% to 224.09, AMD gained 1.8% to 482.93, and Taiwan Semiconductor rose 1.7% to 429.15, all without a scheduled print of their own on Wednesday. The read-through ran from Super Micro's fiscal 2027 revenue guide of 65 to 72 billion against a backlog north of 60 billion, a number that implies sustained server and memory demand well past this quarter.
Cisco Systems closed at 123.88, up 2.9%, in the same session its own results showed revenue of 17.25 billion, up 18% year over year, and AI infrastructure orders of 9.3 billion for the fiscal year. The Technology Select Sector ETF, XLK, gained 1.5%, a fraction of what its loudest members managed individually.
12:30 UTC is when the Bureau of Labor Statistics put July's headline consumer price index at 3.4% year over year and 0.1% for the month, both matching consensus, with core inflation at 2.5% annually. A Kalshi contract on the Federal Reserve holding rates at its September meeting printed as high as 69% in the hour that followed, up from 58% Tuesday evening, before settling near 66% into Wednesday's close. A separate contract on a 25-basis-point September cut stayed pinned near 1-2% throughout, never a live possibility either way.
The VIX closed at 14.55, down 4.8%, its lowest close of the week. A prediction market on the AI industry's own bubble risk barely reacted to any of it, ticking from 12.35% to 14.3%, a small move given how violently individual AI-linked stocks traded on the same day.
Meta opened at 601.07 Wednesday and never traded above that level again, sliding through the first ninety minutes to 585.84 by 14:45 UTC and continuing lower into the afternoon before closing at 578.85, down 3.4%. A search of Wednesday's wires turned up nothing dated to the session itself, only recycled references to a capital-spending forecast and free-cash-flow compression from Meta's own earnings report on July 29, two weeks earlier.
The tape puts the move in a different light. Meta bottomed at 539.03 on July 30 after that report, then rebuilt to 599.12 by Tuesday, an 11.2% rebound over eight sessions. Wednesday's decline erased close to a third of that recovery in a single day, a real reversal inside a real rally, not a fresh leg down and not the news-free plunge a close-only read would suggest.
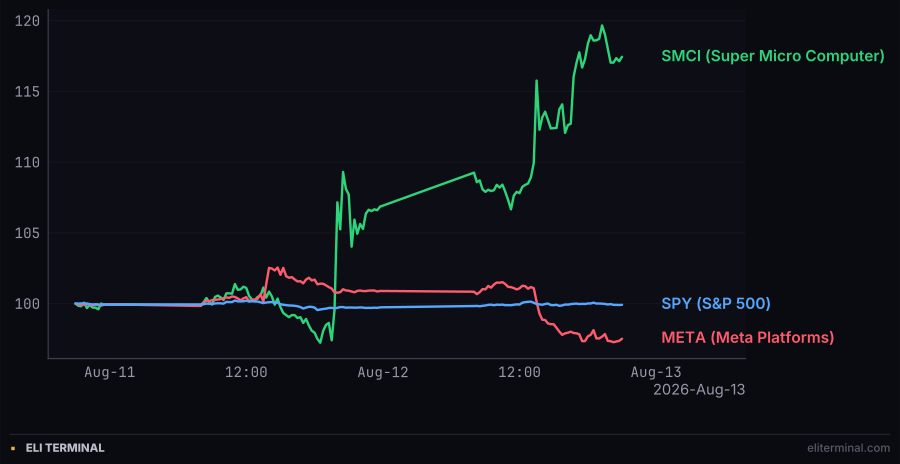
One stock spikes and holds. The other bleeds all session. The index does neither.
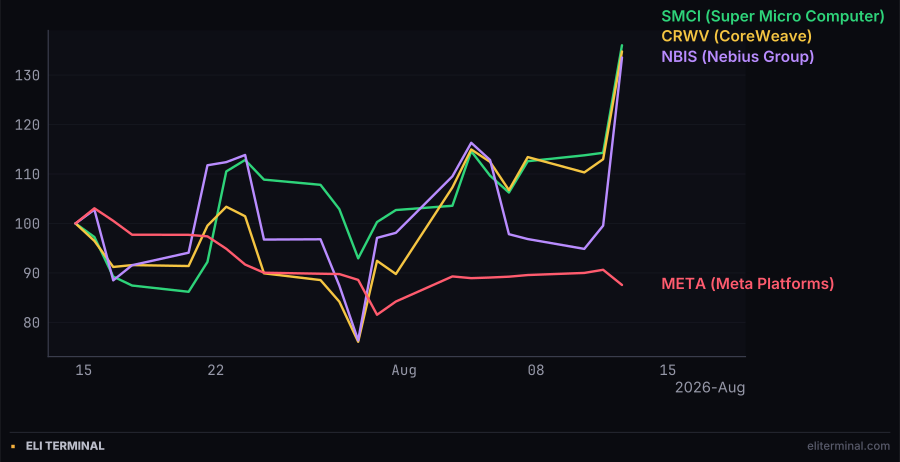
Wednesday's earnings beats broke out of a month of chop. Meta's decline did not break anything; it resumed.
Brent crude ran from about 87.5 near 11:00 UTC Tuesday to an overnight high of 90.07 at 04:00 UTC Wednesday, a climb of roughly 3%, after Houthi forces struck a commercial vessel in the Bab al-Mandeb strait, killing six, and United States Central Command struck a Panama-flagged cargo ship attempting to breach Iran's blockade of the Strait of Hormuz. Both incidents were reported before the New York session opened.
By Wednesday's 4pm close, Brent was back to 88.98 and WTI to 83.27, both up just 0.08% from Tuesday. The New York session gave back nearly the entire overnight move. The 10-year Treasury yield held essentially flat at 4.682%, down two-tenths of a basis point from Tuesday's 4.684%, showing no sign that oil's overnight spike carried through into the rates market once American traders arrived.
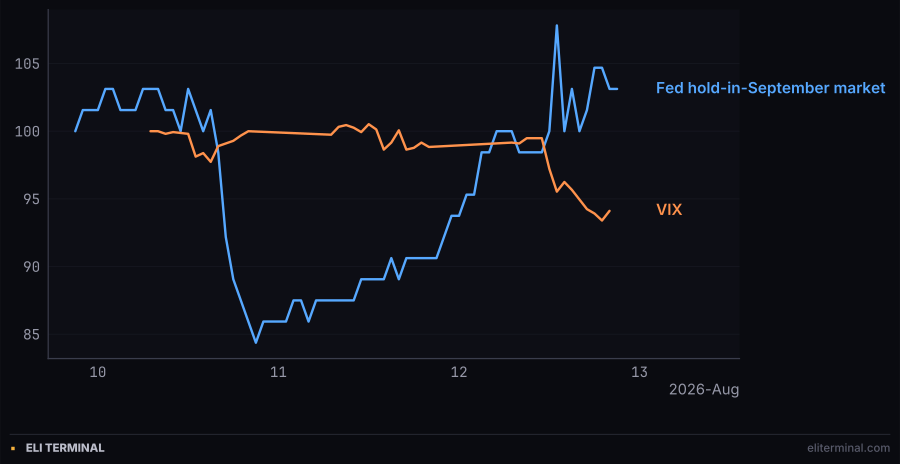
Both lines moved in the same hour Wednesday morning. Neither moved much before it.
08:30 ET Thursday, August 13, is when the July producer price index and weekly jobless claims post, the next data the market gets before it has to decide whether Wednesday's Fed-hold repricing survives a second look. Applied Materials also reports that day, the first read on whether Wednesday's AI-infrastructure earnings pattern extends into semiconductor equipment names or stayed contained to cloud and server operators.