Meta Said "Excess." The Market Prices a 90% Green Open Anyway.
Ten paper put positions, $905 at risk, against a tape that prices a 79% chance Monday closes green and a VIX that never left 16.
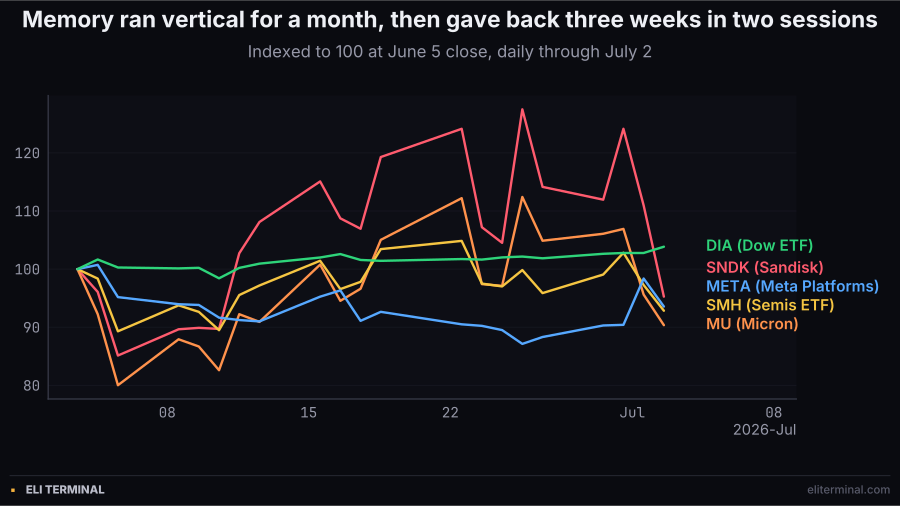
Sandisk was +567% from January 7 to its June 22 peak. It gave back 23.3% of itself in the last two sessions before the holiday.
What actually happened last week
12:35 UTC Wednesday July 1, Bloomberg reported Meta is building "Meta Compute," a cloud business to sell excess AI capacity. Meta gapped 7.9% at the open and closed +8.81%. The SOX fell 6.27% the same session, because "excess" broke the premise that compute is scarce. Goldman's one-delta desk said the quiet part: the first hyperscaler to signal it can slow spending gets rewarded, and its suppliers get repriced.
Thursday the SOX fell another 5.4% and Meta gave the pop back, closing −4.90% at 582.90, just 0.43% above its session low. The June jobs report printed +57K against a ~110K consensus at 12:30 UTC that morning, and the Dow rallied to a record 52,900 anyway. This was rotation, not risk-off: SPY finished the two days at −0.27%, equal-weight closed at a one-month high, MSFT gained 4.69%, and the VIX never traded above 17.19.
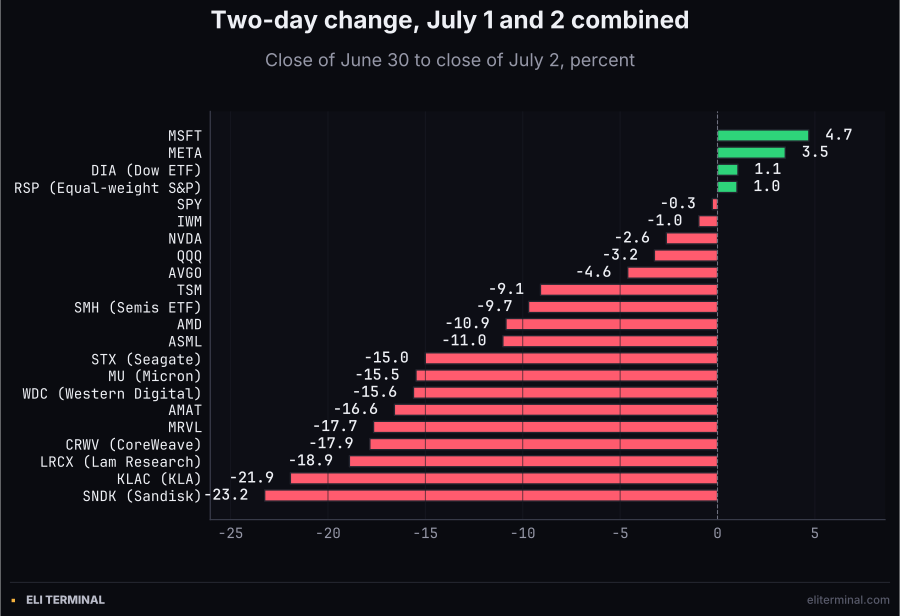
The wreck was surgical. Memory, storage, semicap equipment, and neoclouds took 15 to 23%. NVDA took 2.6%. The Dow went up.
Sandisk is the epicenter and the anatomy matters: 11.06M shares Wednesday and 17.26M Thursday against 2-3M normal, so 4x to 8x volume, and it still trades at 26x forward earnings with 11.5% of the float short. There was no Sandisk filing, no downgrade found, no NAND datapoint. It is a re-rating of a parabolic chart, exactly as you framed it: no liquidity problem, just a multiple being taken away.
Micron is the proof the selling ignores fundamentals. Its June 24 report was the best in memory history, $41.5B revenue and a $50B guide at 86% gross margin, and the stock still lost $202B of market cap in two days. When a market sells THAT print, it is repricing who captures compute economics, not demand.
Your 10am pattern, corrected by 15 minutes
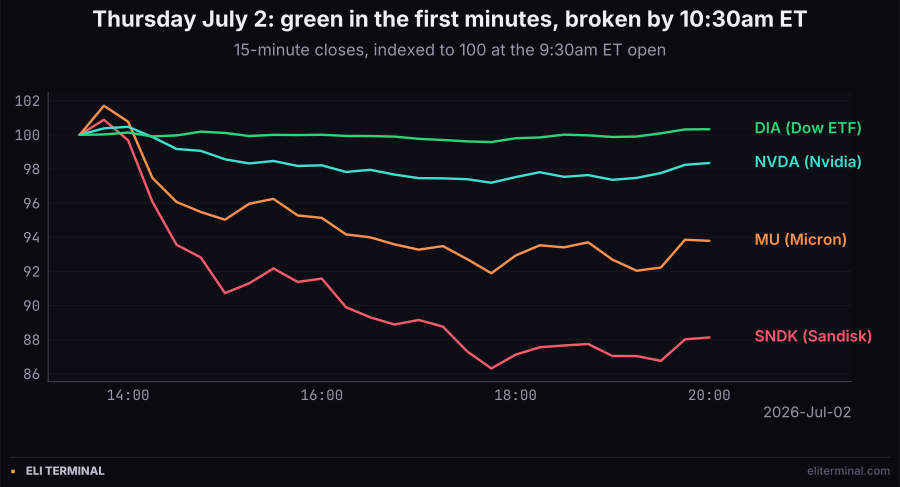
Green in the first 15 minutes, broken by 10:30. Sandisk's single worst leg was 10:15 to 10:30am ET, −3.6% in 15 minutes.
The hourly and 15-minute candles confirm your pattern with one correction. Thursday's dump did not start around 10am, it was mostly finished by 10:30. SNDK and MU opened green, printed their highs in the first 15 minutes, and had absorbed the bulk of the damage by 10:30am ET. NVDA lagged one hour, with its sharpest leg 10:30 to 11:30. Session lows printed 1:30 to 3pm, then everything bounced modestly into the close.
That compresses the trade window. If Monday repeats Thursday, you have roughly 9:30 to 9:45 to get filled into the green open and the move is over by 10:30. A put bought at 10:00 "when the drop starts" is buying the middle of the move, Thursday's tape says the drop starts at 9:45.
The overnight tell: the bounce already happened, offshore
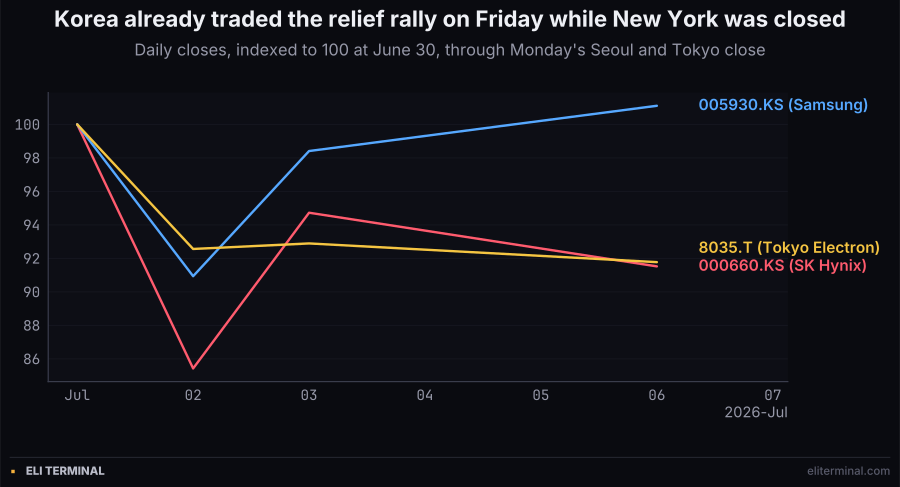
SK Hynix fell 14.6% Thursday, bounced 10.9% Friday with New York closed, then gave a third of it back Monday. Samsung kept going up.
This is the piece the "huge green candle Monday" crowd may be missing. The relief rally already happened, on Friday, in Korea, while US markets were shut: SK Hynix +10.88%, Samsung +8.22%. Monday's Seoul session then split: SK Hynix gave back 3.38%, Tokyo Electron fell 1.2%, but Samsung added another 2.75% and both KOSPI and Nikkei V-shaped off their 02:00 UTC lows to close flat.
US futures spent eleven overnight hours doing nothing: ES flat, NQ −0.21%, YM +0.08% as of 08:00 UTC. A market with a second violent leg queued usually gaps; this one is motionless on an empty calendar. Zero mega-cap earnings and zero macro releases print Monday, the schedule is clean both directions.
Sentiment is genuinely split, which is your setup in one line. Prediction-market money prices a 90% up-open and a 79% up-day for the S&P on thin volume, while the AAII survey has bears at 42.3%, its 21st straight week above average. Recession odds on the deepest Kalshi contract FELL 4 points to 8.5% through the selloff window. Nothing in the probability layer confirms a crash; everything confirms a crowd leaning green at the open, which is precisely what makes the open the right entry for a fade and the wrong one for a chase.
The structural problem with "single-day puts on Sandisk"
Verified from the chains this morning: Monday expiry exists on exactly four tickers: SPY, QQQ, NVDA, META. Sandisk, Micron, Western Digital, Seagate, AMD, and even SMH have nothing until Friday July 10.
MU Jul 10 5% OTM put (925): $3,976 per contract
Budget-fit SNDK strike: 785P at $100, which is 55% out of the money
META Jul 6 0DTE 565P: $103 · NVDA Jul 6 190P: $65 · QQQ Jul 6 691P: $40
So Sandisk, your named favorite, is untradeable at $100 a position. One at-the-money contract costs $12,970, and the only strikes that fit the budget need the stock to fall a further 50% by Friday. The debate killed it 2/10 bear, 1/10 bull-residual, the lowest scores on the board. Same verdict on Micron: the near strikes cost 40x the position size. The wreck names price their own downside at 65 to 79% of at-the-money premium even 5% out, the market already paid for the crash that happened.
The names you CAN short with Monday expiry are the ones the wreck barely touched. That asymmetry is the whole trade design problem, and it is why the book below looks the way it does.
What the debate produced
Seven candidates each got a bear analyst building the strongest short case and a bull analyst attacking it, plus one devil's advocate arguing the chop day that kills everything. No bear scored above 4/10 conviction. That is the honest headline: this is a low-probability book, and every agent that touched the math said so.
| Candidate | Bear / Bull residual | One-line verdict |
|---|---|---|
| CRWV | 4 / 4 | Best thesis on the board. Meta Compute is CoreWeave's business model with free money behind it. Bernstein calls the model unsustainable, target 67. Survives independent of Monday's tape. |
| MU | 4 / 3 | Real re-rating logic, untradeable structure. Near puts cost $4,000 a contract. |
| META | 3 / 2 | Only idiosyncratic story with a Monday expiry. The margin narrative is live but 4 days stale; breakeven needs Thursday's whole move repeated. |
| NVDA | 3 / 3 | The unresolved asymmetry: its customers-turned-competitors repriced 15-23%, NVDA repriced 2.6%. Neither bought with quality nor sold with the complex. |
| QQQ | 3 / 3 | The index expression of the rotation. MSFT and AMZN mechanically cap the downside, Thursday proved it. |
| LRCX/semicap | 3 / 3 | Right domino, wrong strikes. In-budget puts sit 20% out of the money. |
| SNDK | 2 / 1 | Epicenter, untradeable. Rejected on structure, not on story. |
The chop analyst's number is the one to hold onto: every 3% out-of-the-money 0DTE put needs roughly a 3-sigma down day just to break even, because VIX 16 implies a 1.0% daily standard deviation. He puts 38% on a sub-0.7%-range nothing day, and reads the overnight tape (flat futures, Samsung green, V-shaped Asian indices) as stabilization, not dead-cat. Your "dead cat bounce means a massive drop is coming" prior gets one supporting datapoint, SK Hynix giving back a third of Friday, and several opposing ones.
The book
Given all of that, here is how I would deploy the hypothetical $1,000 if forced to hold your scenario, green open then a hard fade. Sized $65 to $116 per line, ten lines, $905 total. Six lines die at 4pm; four are Friday-dated and get marked at Monday's close.
| # | Contract | Cost | Needs (by 4pm ET) | Role |
|---|---|---|---|---|
| 1 | META Jul 6 565P ×1 | $103 | −3.1% to 565 | The idiosyncratic short. The margin story is Meta's own words. |
| 2 | META Jul 6 555P ×2 | $90 | −4.9% to 555 | Convexity behind line 1. Pays 6x at Thursday's repeat. |
| 3 | QQQ Jul 6 696P ×1 | $84 | −2.4% to 696 | Nearest-the-money index fade. The most likely line to pay anything. |
| 4 | QQQ Jul 6 691P ×2 | $80 | −3.1% to 691 | Behind line 3, needs worse than Thursday's worst. |
| 5 | NVDA Jul 6 190P ×1 | $65 | −2.5% to 190 | The catch-down. NVDA never repriced with its complex. |
| 6 | NVDA Jul 6 185P ×5 | $95 | −5.1% to 185 | Deep catch-down lottery, 5 contracts at $0.19. |
| 7 | CRWV Jul 10 75P ×1 | $95* | MTM: −5% helps, −8% doubles | The real thesis. Scored on Monday's mark, not expiry. |
| 8 | CRWV Jul 10 70P ×1 | $76 | MTM, further out | Behind line 7. |
| 9 | LRCX Jul 10 280P ×1 | $116 | MTM vol pop on −3-5% day | Semicap, the longest-duration casualty if capex slows. |
| 10 | SPY Jul 6 722P ×25 | $100 | −3.1% index crack | The free-tail lottery: index 0DTE downside is priced near zero. |
*Line 7 uses the 71 strike at $0.95 if the 75s reopen above $100. All premiums are Thursday last-trade prints; bid/ask were empty pre-open and every line reprices at 13:30 UTC. Costs are approximations against a $100-per-line cap.
Execution discipline, or the book is noise
Entry: 9:30 to 9:45am ET, into the green open, and only if it is green. A 90% priced up-open is what makes 0DTE puts cheap at 9:35. If the market opens red instead, the fade already started without you and the entries are worse, stand down on lines 1 to 6 and reassess.
The tell comes by 10:30. Thursday's entire break was done by then. If the tape is still green at 10:30am ET, the pattern is not repeating and the six Monday-expiry lines are dead money into a 4pm zero, no averaging down, no "it needs more time." There is no more time, that is the instrument.
Honest expected value: negative. Roughly: 55 to 65% chance this is a flat or green day and the book loses $700 to $850 of the $905. Maybe 25% chance of a Thursday-magnitude fade, where lines 3, 7, and 9 pay, line 1 fights for breakeven, and the book roughly recovers cost. Maybe 10 to 15% chance of the second violent leg, where the convexity lines take the book to 3x to 8x. You are buying a cheap claim on a specific Monday shape that the overnight evidence says is the less likely one. That is the record speaking, not caution.
Scorecard, added 20:00 UTC July 6
Monday closed green and grinding: SPY 751.28 (+0.87%), QQQ 722.82 (+1.43%), META 600.29 (+2.98%), NVDA 195.55, VIX 15.57 at a fresh low. All seven Monday-expiry lines expired worthless. The three July 10 lines lost 35 to 78% of their marks to the rally and the vol crush.
| # | Line | Cost | Close mark | P&L |
|---|---|---|---|---|
| 1 | META Jul 6 565P ×1 | $103 | expired, META 600.29 | −$103 |
| 2 | META Jul 6 555P ×2 | $90 | expired | −$90 |
| 3 | QQQ Jul 6 696P ×1 | $84 | expired, QQQ 722.82 | −$84 |
| 4 | QQQ Jul 6 691P ×2 | $80 | expired | −$80 |
| 5 | NVDA Jul 6 190P ×1 | $65 | expired, NVDA 195.55 | −$65 |
| 6 | NVDA Jul 6 185P ×5 | $95 | expired | −$95 |
| 7 | CRWV Jul 10 71P ×1 | $95 | $21 (last 0.21) | −$74 |
| 8 | CRWV Jul 10 70P ×1 | $76 | $18 (last 0.18) | −$58 |
| 9 | LRCX Jul 10 280P ×1 | $116 | $75 (last 0.75, wide) | −$41 |
| 10 | SPY Jul 6 722P ×25 | $100 | expired, SPY 751.28 | −$100 |
| Book | $904 | $114 | −$790 (−87%) |
The pre-open estimate said 55 to 65% odds the book loses $700 to $850. It lost $790. Two backtest rows hit, both bull-side: META above 590 (the margin re-rating is done for now) and CRWV above 85 (dip-buyers won the day). VIX closing at 15.57 is the opposite of the regime-crack row.
One thing survived for the bears. SNDK gapped up 4.6% to 1824, printed 1837, and gave back the entire bounce to close at 1744.43, three cents below Thursday. LRCX did the same, from +4.1% at the open to −0.34%. The two most broken names could not hold a bid on a day the index rallied and vol collapsed. If Tuesday takes SNDK below today's 1713 low, the failed-retrace short activates with defined risk; if the names reclaim their opening gaps, the wreck is over.
Internal desk note, paper exercise only, nothing here is investment advice and no positions will be taken. All timestamps UTC. Premiums are Thursday July 2 last trades from chains with empty bid/ask pre-open and will reprice at the July 6 13:30 UTC open. Scored against the 20:00 UTC close. Sources: Bloomberg (Meta Compute, July 1), CNBC (Meta cloud margins, July 2), BLS Employment Situation (July 2), AAII Sentiment Survey (July 2), MarketWatch (July 5), exchange data via Yahoo, KRX, TSE, CME; odds via Kalshi and Polymarket data, cited as data, not linked.