Stocks, bonds, and oil, March 9-11
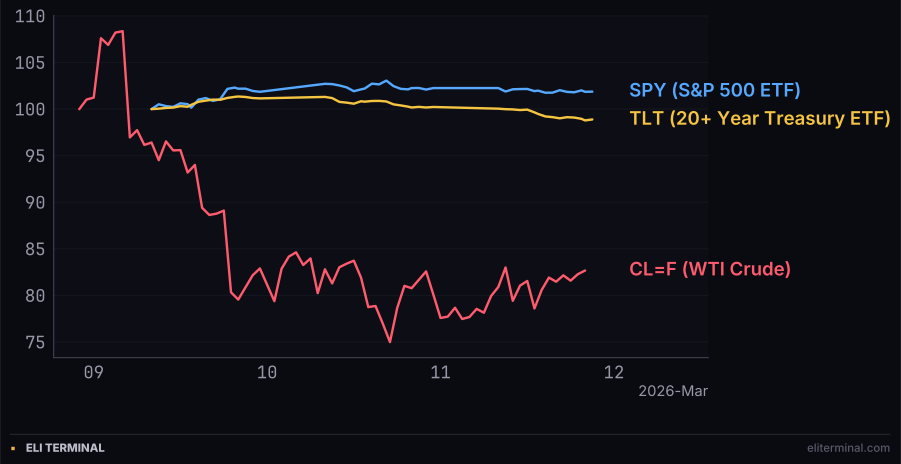
Same three days, same index start. Stocks and bonds barely move. Oil goes on a 24-point round trip.
Oracle rose 9.2% on a cloud-revenue beat, West Texas crude spiked above 119 and crashed near 77 before closing up 4.55%, and the S&P 500 barely moved.
Same three days, same index start. Stocks and bonds barely move. Oil goes on a 24-point round trip.
0.3% month over month, 2.4% year over year: February's headline consumer price index matched the consensus forecast to the decimal at 8:30am ET Wednesday. Core CPI came in at 0.2% and 2.5%, also exactly as expected. Rent rose just 0.1%, the smallest increase since January 2021.
Sonu Varghese, chief macro strategist at Carson Group, called the report the calm before the storm, noting the data predates March's oil spike and won't capture rising gasoline costs until next month's release. The S&P 500 ETF held inside a six-point range through the release and closed at 676.33, down 0.13% on the day. The Nasdaq 100 ETF closed essentially flat, down 0.01%.
West Texas Intermediate topped out at an intraday 119.48 a barrel in the first hours of Monday's global session, at 02:00 UTC, its highest print since the war began. By 19:00 UTC the same day, in the middle of the New York afternoon, WTI had plunged to an hourly low of 81.19, a roughly 15% drop inside one hour with no single headline attached to it anywhere in that afternoon's wires.
Tuesday extended the slide to an intraday low of 76.73 at 17:00 UTC before crude closed the day at 83.45, down 11.9% from Monday's close. Wednesday reversed course: after a session low of 81.79, WTI chopped between 83 and 89 through the Asian and European hours, then climbed almost without interruption from a 13:00 UTC print near 83.52 to an 88.41 print by 20:00 UTC, finishing the day at 87.25, up 4.55%. Brent tracked the same shape and settled at 91.98, up 4.76%.
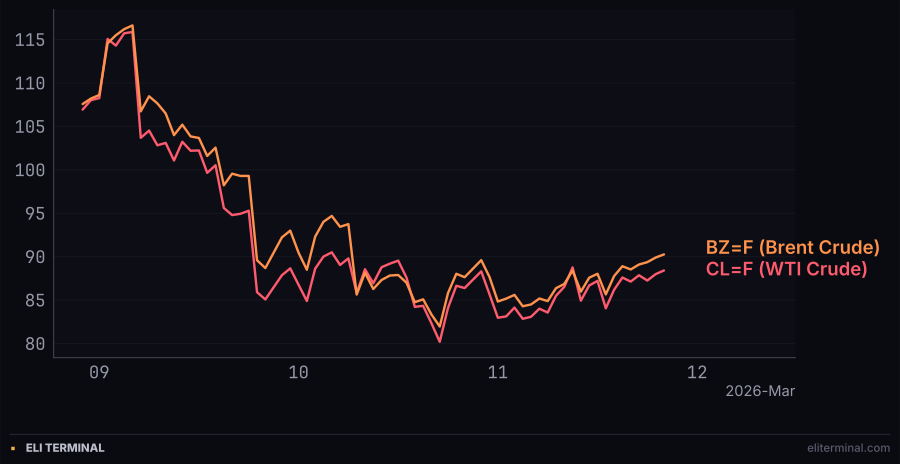
Brent and WTI moved as one instrument across the entire three-day swing.
The International Energy Agency agreed Wednesday to release 400 million barrels of crude from members' strategic reserves, more than double the amount unlocked after Russia invaded Ukraine and roughly a third of the group's total 1.2 billion barrel holdings. The U.S. share, 172 million barrels from the Strategic Petroleum Reserve, is the largest single national contribution in the release.
Crude rallied through the same Wednesday afternoon this news circulated. A supply announcement sized to cap the war premium landed on the one session this week prices were climbing, not falling.
Tuesday, Defense Secretary Pete Hegseth told reporters that day would be "our most intense day of strikes" inside Iran; crude fell 11.9% anyway. Wednesday brought a different kind of escalation: CENTCOM said it had destroyed 16 Iranian boats it identified as laying naval mines near the Strait of Hormuz, and Iran's Revolutionary Guard Corps declared that any American, Israeli, or allied vessel transiting the strait was now a legitimate target.
Neither statement carries a public timestamp precise enough to isolate against the 13:00-to-20:00 UTC rally in crude. The war entered its twelfth day Wednesday, counting from the U.S. and Israeli strikes that opened it on February 28.
The 10-year Treasury yield rose 7 basis points to 4.208%, up 1.74% on the day; the 30-year climbed to 4.857%. The Treasury ETF TLT fell 1.29%, its worst session of the week. None of that traces to the CPI print, which was a non-event; the timing lines up instead with the hours crude spent climbing.
The S&P 500 ETF and the Nasdaq 100 ETF closed within 0.13% of flat. The Russell 2000 ETF fell 0.20%. Equities read Wednesday as a wash. Rates read it as a war that had just gotten more expensive to insure against.
Gold closed at 5,167.40 an ounce, down 1.19%, even as WTI rose 4.55% and the war both commodities are supposed to trade on entered its twelfth day. Silver fell harder, down 4.51%; copper slipped 0.99%.
The metals complex had its own reason to sell off: a seven-basis-point rise in the yield an investor forgoes by holding gold instead of a bond. Crude had a physical supply story tied to a closed strait; gold, that day, had only the rates story, and the rates story pointed down.
Oracle closed at 163.12, up 9.18%, a day after its fiscal third-quarter report showed cloud revenue up 44% to 8.9 billion dollars and cloud infrastructure revenue up 84%. The company raised its fiscal 2027 revenue guidance to 90 billion dollars. Oracle actually closed lower Tuesday, at 149.40; the entire move showed up at Wednesday's open.
Taiwan Semiconductor rose 2.15% to 354.56 a day after reporting record February revenue of roughly NT$317.66 billion, up 22.2% from a year earlier on 3-nanometer chip demand. Both moves trace to disclosures made before Wednesday's session, not to anything in the war.
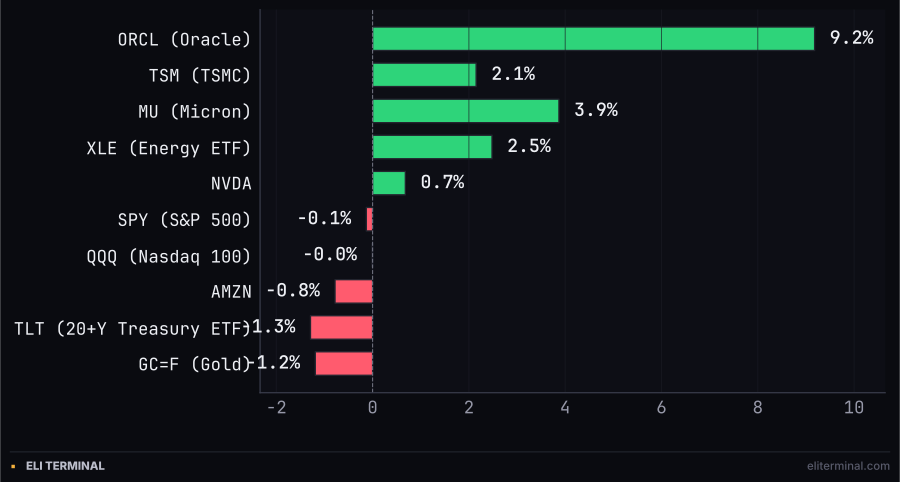
Oracle alone moved more than the entire index. Gold and bonds fell together at the other end.
Micron closed at 418.69, up 3.87%, the largest gain among the week's mega-cap chip names, on a day it disclosed nothing new. DRAM, NAND, and HBM prices have risen 80% to 90% since the fourth quarter of 2025 on AI-driven shortages, a trend already running before Wednesday.
Nvidia, AMD, and Tesla also closed higher, up 0.68%, 0.79%, and 2.15% respectively. Amazon was the outlier in the group, down 0.78%. None of the four had a company-specific catalyst dated to Wednesday.
A market pricing a U.S. invasion of Iran before 2027 moved from 27.5% Tuesday to 29.5% Wednesday, a two-point gain on the day oil rebounded 4.55%. Monday, the same market had jumped to 34.5% alongside oil's spike above 119.
Recession odds told the same story. A market on a U.S. recession by the end of 2026 held flat at 28.5% both Tuesday and Wednesday, having fallen back from 36.5% on Monday's oil peak. A separate market on a formal U.S. declaration of war against Iran by year-end stayed pinned near 10.5% through the entire week, regardless of what oil did on any given day.
Bonds treated Wednesday's rebound as real, moving the 10-year yield 7 basis points. The odds markets treated it as noise left over from Tuesday's crash.
Weekly jobless claims are due Thursday, and the Federal Reserve's policy meeting concludes March 18, the first scheduled venue where officials weigh a rebounding oil price against a CPI report that still looked tame in February.