The month around February 17
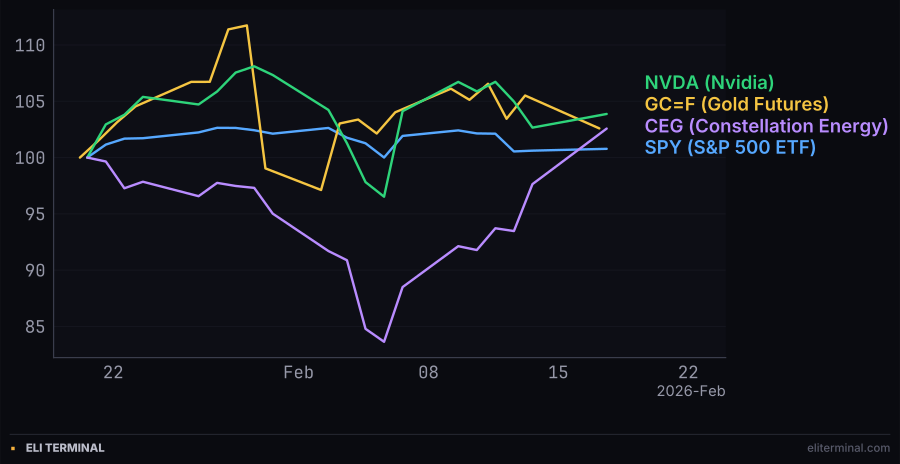
Constellation spent three weeks climbing out of a late-January hole. Gold spent Tuesday giving back a piece of its own run.
Gold fell 2.8% to close below $5,000 an ounce, Constellation Energy jumped 5.1% on one Texas power deal, and Medtronic cratered before 7am Eastern, while the S&P 500 closed up just 0.16%.
Constellation spent three weeks climbing out of a late-January hole. Gold spent Tuesday giving back a piece of its own run.
The SPY closed Tuesday at 682.85, up 0.16% from Friday's 681.75, since Monday was a market holiday. The Nasdaq-100 fund slipped 0.10% to 601.30 and the Dow fund added 0.12% to 495.85. None of those numbers hint at what actually printed: an expanded Nvidia-Meta chip pact, a single power contract that moved Constellation Energy 5%, a Geneva readout tied to gold's worst day in two weeks, and two earnings reports that both beat and both got sold.
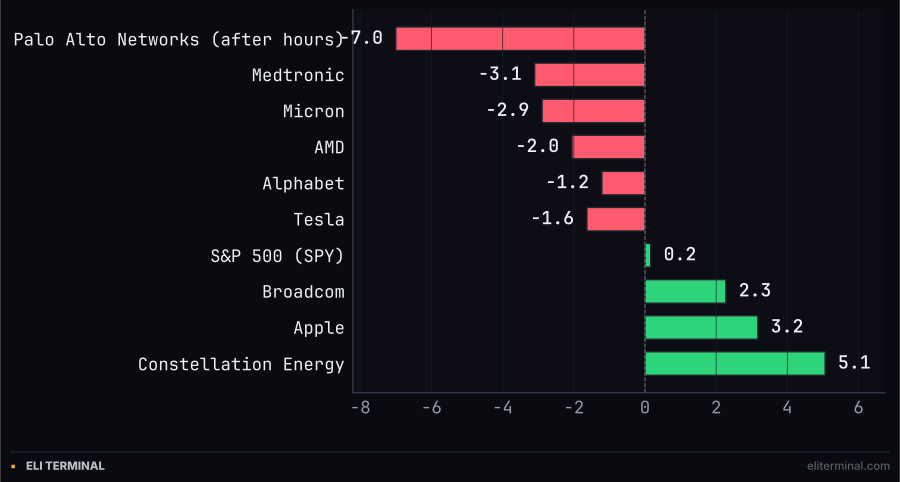
Every one of the ten bars has a name attached to it except the two on the far right.
Nvidia and Meta announced an expanded, multiyear, multigenerational infrastructure partnership before Tuesday's bell: Meta will deploy millions of Nvidia's Blackwell and Rubin GPUs alongside Nvidia's Grace CPUs, the first large-scale deployment of Grace-only servers at a hyperscaler that normally buys general-purpose chips from Intel or AMD. Chip analyst Ben Bajarin of Creative Strategies put the contract's scale in the tens of billions of dollars.
Nvidia rose as much as 2.4% in premarket trading on the news, toward 189. By the 9:30am ET open the stock had given all of that back and more, trading down to an intraday low of 179.18, before climbing back through the session to close at 184.97, up just 1.18% on the day. Meta, the buyer in the deal, closed at 639.29, down 0.08%, essentially unmoved by an agreement analysts sized in the tens of billions.
Constellation Energy opened Tuesday at 289.49. By 9:30am ET the stock had already jumped past 298, and it touched an intraday high of 305.80 near 10:30am before easing back to close at 303.01, up 5.06% on the day. The move traces to a single announcement: Constellation's Calpine unit and CyrusOne said they had agreed to a new 380-megawatt contract to power a data center adjacent to the Freestone Energy Center in Texas, with an exclusive option on an additional 380 megawatts in a second phase.
The contract lands in the same week as Nvidia's expanded Meta deal, on the same side of the same trade: someone has to power the chips. Constellation's stock did the arithmetic in real time, in one 15-minute bar.
Iranian Foreign Minister Abbas Araghchi told reporters in Geneva on Tuesday that the United States and Iran had reached "a general understanding on a set of guiding principles" after a second round of nuclear talks, mediated by Oman, that followed the first round held in Muscat on February 6. "This does not mean that we can reach an agreement quickly," Araghchi said, "but at least the path has begun." No date was set for a third round; both sides agreed to begin drafting the text of a potential agreement instead.
Gold opened Tuesday at 5,020 an ounce and fell as low as 4,847.80 before closing at 4,882.90, down 2.77%, its sharpest one-day decline in two weeks. The bulk of the drop landed between 8am and 9am ET, ahead of the New York equity open and ahead of any confirmed readout time from Geneva, so the exact join between the talks and the futures market cannot be made with precision. What can be said plainly: a session that produced real, on-the-record language about de-escalation was also gold's worst day since the metal's run toward its late-January high near 5,318.
Medtronic's fiscal third-quarter numbers, released before Tuesday's open, beat on every headline metric: revenue of $9.0 billion against a $8.89 billion estimate, adjusted earnings per share of $1.36 against $1.34 expected, and cardiac ablation revenue up 80% globally on strength in its pulsed-field ablation portfolio. The stock did not treat it as a beat.
Medtronic actually opened premarket firmer, near 101, then broke inside the same hour, falling to an intraday low of 93.64 by 7am ET, a swing of more than 7% in under sixty minutes. It clawed back through the rest of the session to close at 96.41, down 3.10% on the day. The reversal points at guidance and margins rather than the top line: Medtronic reiterated its full-year outlook rather than raising it after a beat, and investors read the lack of an upward revision as a signal that the strong quarter will not carry through the rest of fiscal 2026.
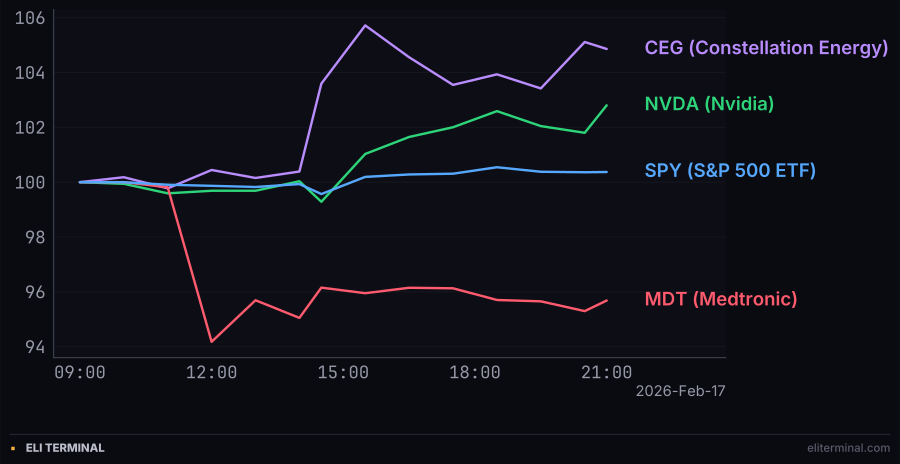
Three single-name stories, one nearly flat index line running underneath all of them.
Palo Alto Networks closed the regular session at 163.50, down 2.07% ahead of its own earnings release after the bell. The fiscal second-quarter numbers beat: adjusted earnings per share of $1.03 against a 94-cent estimate, and revenue of $2.59 billion, up 15% year over year, against $2.58 billion expected. The stock slumped roughly 7% in after-hours trading anyway.
The guidance did the damage. Palo Alto forecast fiscal third-quarter adjusted earnings of 78 to 80 cents a share, short of the 92-cent estimate compiled by LSEG, and cut its full-year adjusted EPS range to $3.65 to $3.70 from $3.80 to $3.90. Deal-related costs more than doubled year over year to $24 million, a direct line item from the company's acquisition spree this year, most notably its purchases of CyberArk and Chronosphere.
Apple closed at 263.88, up 3.17%, its largest gain among Tuesday's megacaps, on a session where Oppenheimer analyst Samik Chatterjee raised his price target to $340 from $325 ahead of the bell. The note flagged Apple's AI-related opportunity alongside a more gradual AI rollout than some competitors, a mixed framing for a target hike this large.
The same day carried the opposite headline in print: Forbes published a piece titled "Why Apple Stock's 2026 Rally Is Under Threat," citing softening iPhone demand in China against domestic competition from Huawei and rising cost pressure across the smartphone sector. Both stories ran Tuesday. Only one showed up in the closing price.
The VIX opened at 21.74, climbed to a session high of 22.96 by 11:00am ET, then dropped more than two points within that same hour to 20.49, a round trip inside sixty minutes that matches no single headline found across Tuesday's coverage. The index kept drifting lower into the New York afternoon, printing a fresh session low of 19.76 near 2:00pm ET, in the same broad window Geneva's "guiding principles" language was working through the wires, before closing at 20.29, down 1.50% on the day.
Credit markets saw none of it. The high-yield bond fund HYG closed at 80.81, down 0.05%, and the investment-grade fund LQD closed at 111.70, up slightly. Whatever drove the morning's volatility round trip, it stayed contained to the volatility market itself.
The Federal Reserve releases the minutes of its January 27-28 meeting at 2:00pm ET Wednesday, the meeting at which the Federal Open Market Committee held its target range at 3.50% to 3.75%. Tuesday's session already carried that anticipation in its framing even though the minutes had not yet printed. Wednesday's economic calendar also brings Industrial Production and Capacity Utilization at 9:15am ET and New Residential Construction at 8:30am ET, plus earnings from Analog Devices and Booking Holdings.
The Advance Monthly Sales for Retail and Food Services report originally listed for Tuesday's calendar did not print on schedule; Census Bureau data releases have been running behind since the funding lapse earlier this year, and the January retail sales figures were not confirmed as released on February 17.