One-day moves, February 6
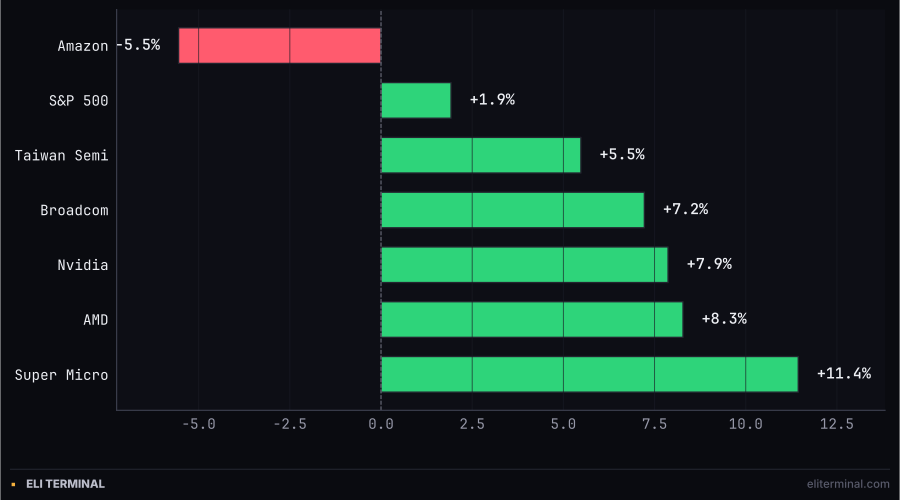
The five names hit hardest in the week's selloff led Friday's rebound. Amazon, the name that started the selloff, kept falling.
Nvidia rose 7.9% and Bitcoin clawed back 12% of Thursday's rout, while Amazon fell 5.6% on a same-day downgrade even as the S&P 500 closed up 1.9%.
The five names hit hardest in the week's selloff led Friday's rebound. Amazon, the name that started the selloff, kept falling.
60,074.80 is where Bitcoin bottomed, inside the 00:00-01:00 UTC hour Friday, which is 7 to 8pm Thursday evening on the East Coast. It had fallen from near 73,160 Thursday morning, an almost 18% peak-to-trough drop inside a single day, one of the fastest single-session declines crypto traders had logged since the FTX collapse in November 2022.
By 13:00 UTC Friday, half an hour before the New York opening bell, Bitcoin had already climbed back to 67,312, a gain of more than 12% off the overnight low. The recovery was substantially complete before a single equity trader in Manhattan could act on it. Bloomberg tied the overnight low to a forced deleveraging spiral across futures and perpetual markets.
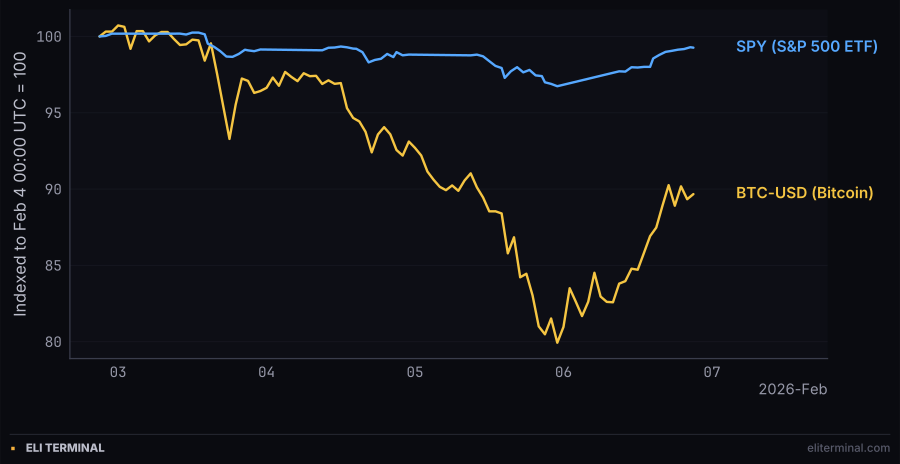
Bitcoin's round trip dwarfed the index's. The equity low and the crypto low did not land in the same hour.
Super Micro gained 11.44% to 34.38. AMD gained 8.28% to 208.44. Nvidia gained 7.87% to 185.41. Broadcom gained 7.22% to 332.92, and Taiwan Semiconductor gained 5.48% to 348.85. These were the exact five names that had absorbed the heaviest selling since Tuesday.
Nvidia's gain arrived almost entirely in one half hour. The 14:30 UTC bar, the first full 30 minutes after the opening bell, opened at 176.69 and closed at 182.65, a 3.4% move inside thirty minutes that accounted for most of the day's total gain. From there Nvidia added only another point and a half into the 21:00 UTC close.
D.A. Davidson cut Amazon to Neutral from Buy on Friday and lowered its price target to 175 from 300. Analyst Gil Luria's note argued AWS is "losing the lead," pointing to AWS's 24% year-over-year growth against Microsoft Azure's 39% and Google Cloud's 48%. Amazon closed at 210.32, down 5.55%, its worst two-session stretch since Thursday's earnings release.
Thursday's report was the actual source of the week's selloff: Amazon guided 2026 capital spending toward roughly 200 billion dollars, more than 50 billion above what Wall Street had modeled, and the stock fell more than 11% in the after-hours session that followed, part of a broader trillion-dollar wipeout across Big Tech that week. Friday's downgrade landed on top of that, not after it faded.
Friday was supposed to be the day the Labor Department released January's Employment Situation report. A partial government shutdown that ran from January 31 through February 4 pushed the release back five days, to February 11, so no official payrolls number crossed the wires Friday at all.
What did print, on the two days before, was worse than the delayed report is expected to be. ADP counted private payrolls up just 22,000 in January against a 45,000 forecast. Challenger, Gray and Christmas tallied 108,435 announced job cuts for the month, the highest January total since 2009, when 241,749 cuts were announced during the financial crisis. Neither report slowed Friday's rally by the time markets opened.
Oracle rose 4.65% to 142.82. Palantir rose 4.53% to 135.90. Palo Alto Networks rose 2.94% to 159.32, and Microsoft rose 1.90% to 401.14. None of the four matched the chip names' gains, but the direction was uniform, a sign Friday's buying reached past the five hardest-hit chip stocks into the broader AI-adjacent software list.
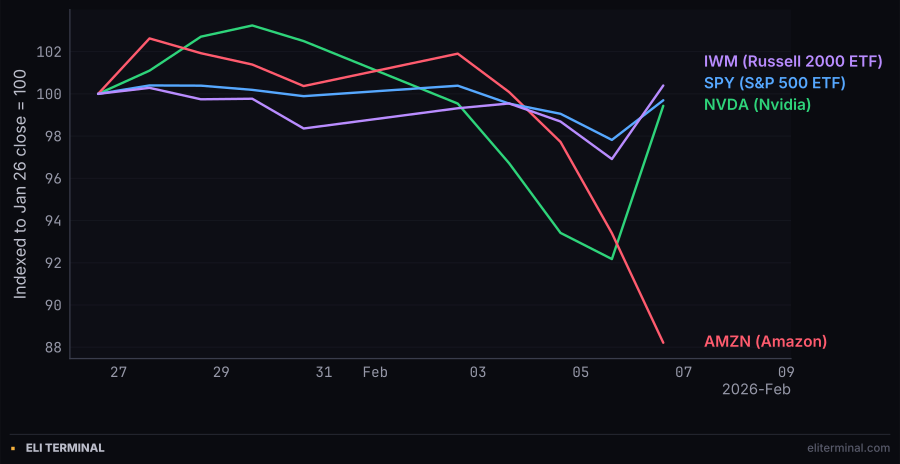
Nvidia and Amazon fell together into Thursday. Only one of them turned Friday.
The VIX closed at 20.37, down 6.43% from Thursday's 21.77, still elevated against the mid-teens level it held two weeks earlier. Oil rose only 0.41% to 63.55, the dollar index eased 0.19% to 97.63, and the 10-year yield held at 4.21%, essentially flat. None of the standard risk gauges moved by more than a rounding error on a day when five stocks moved 5% or more.
Gold was the exception, up 1.85% to 4,951.20, a bigger move than the 0.19% dollar decline typically produces on its own. No fresh gold-specific headline crossed Friday's wires to explain the gap, and it sits alongside a rally in risk assets rather than against one, which is not the usual pairing for a gold bid that size.
Two scheduled releases that Friday skipped are still coming due. The delayed January jobs report lands February 11, and the January consumer price index, also pushed back by the shutdown, follows on February 13. Both were the actual tests the market had circled before the shutdown scrambled the calendar, and neither has printed yet.
Whether Friday's snapback in the five chip names holds through those two releases, or fades the way Amazon's own bounce never started, is the question the week ahead answers. Amazon's stock gave no indication Friday that its capex-guidance selloff was done.