One month, five very different paths
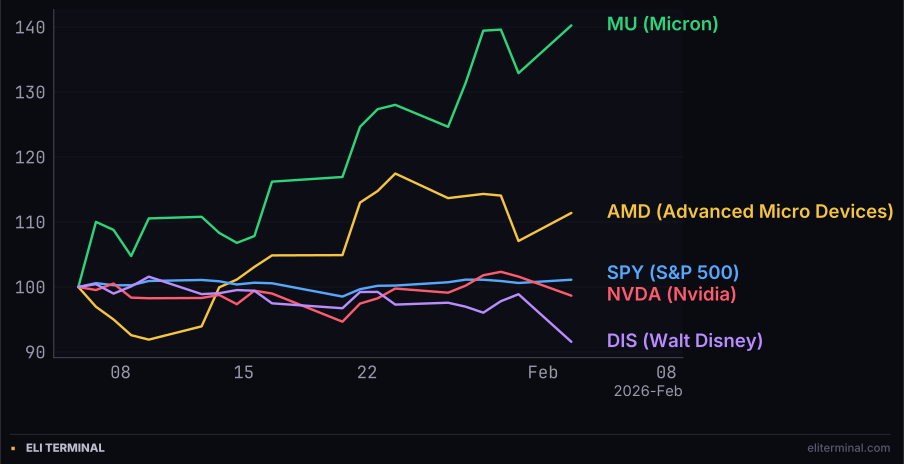
Micron and AMD's February 2 gains extend a month-long climb. Nvidia and Disney never joined it.
Micron gained 5.5% and Disney lost 7.4% in the same session, both moves essentially settled by midday, while Nvidia drifted lower all day even as the S&P 500 closed up 0.5%.
Micron and AMD's February 2 gains extend a month-long climb. Nvidia and Disney never joined it.
52.6% is where the Institute for Supply Management's manufacturing index landed for January, released at 10 a.m. Eastern, up from 47.9% in December and the first reading above the 50 expansion line in 26 months. New orders jumped to 57.1% from 47.4%, the first expansion in that component since August.
The S&P 500 opened at 689.58, within a point of Monday's eventual low, then climbed almost without interruption to close at 695.41, up 0.5% and a few ticks under the day's high of 696.93. The Nasdaq 100 did the same thing more sharply: opened at 618.70, closed at 626.14, up 1.2% from the opening print alone. The Dow and Russell 2000 both opened near their lows and closed within a point of their highs.
Micron opened at 412.18 and closed at 437.80, a 6.2% intraday gain on top of Friday's close, for a 5.5% day over day. AMD opened at 235.77 and closed at 246.27, up 4.5% from its own open, 4.0% versus Friday. Both held their opening gains through the session rather than fading them, the same shape as the broader indexes, just steeper.
Down 2.9% versus Friday is where Nvidia finished, drifting from an open at 187.20 to a close at 185.61 on a day almost everything else in chips was green. The stock has now fallen for four straight sessions since Chinese customs blocked shipments of its H200 processor in mid-January, a freeze that has kept Nvidia locked out of its largest addressable market while peers rallied on the same macro print.
Palantir told a quieter version of the same story, sliding from a session high of 150.94 to a close of 147.76, down 2.1% from the open. The company's fourth-quarter results were due after the closing bell, with a webcast at 5 p.m. Eastern, and whatever the market was doing with the stock ahead of that release, it wasn't buying.
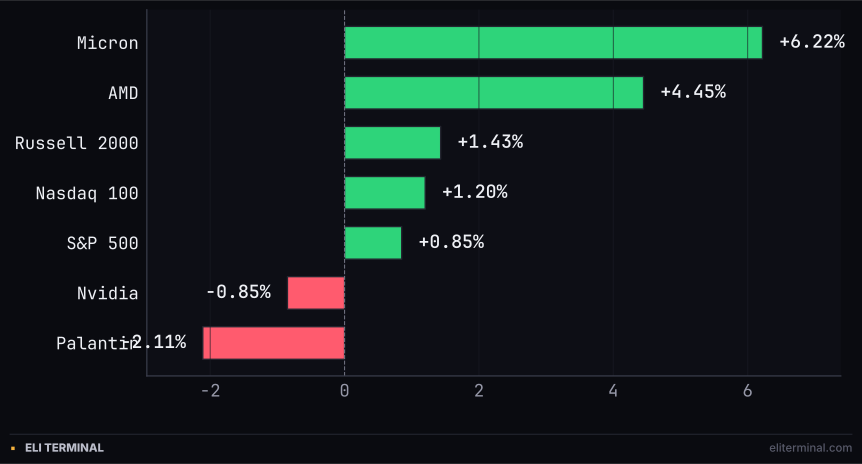
Every index and both memory-adjacent chipmakers gained ground after the open. Nvidia and Palantir gave it up.
26.0 billion dollars is what Disney reported in fiscal first-quarter revenue, up 5% from a year earlier and ahead of analyst estimates. Net income fell to 2.48 billion dollars, or 1.34 dollars a share, down from 2.64 billion and 1.40 dollars a year ago, and total segment operating income dropped 9% to 4.6 billion dollars from 5.1 billion.
Streaming was not the problem. Disney+ and Hulu operating income rose 72% to 450 million dollars on revenue up 11% to 5.35 billion, and the company guided the next quarter's streaming operating income to roughly 500 million, up about 200 million from a year ago. The damage sat in Sports, where operating income fell 23% to 191 million dollars, largely the residue of ESPN's two-week blackout on YouTube TV last fall, a dispute that Variety reported cost the segment 110 million dollars on its own.
The stock opened at 104.01, already down about 7.8% from Friday's 112.80 close before the first trade printed. It rallied intraday to 108.61, cutting the loss to roughly 3.7%, then rolled over and closed at 104.45, down 7.4% on the day and eight cents off the session low. The recovery attempt failed in the same session it started.
4.71% is how much WTI crude fell Monday, settling at 62.14 against Friday's 65.72. Almost none of that move happened during the New York session. Crude was already down near 61.4 to 62.3 dollars by the time futures opened for the week Sunday evening and ground lower into Monday morning, then sat in that same narrow band through the entire 13:30 to 21:00 UTC trading day before closing at 62.14.
Eight OPEC+ producers meeting virtually Sunday reaffirmed a decision to pause production increases through March. Separately, Kazakhstan's Caspian pipeline disruptions, which had helped push WTI from the mid-50s toward 65 during January, eased over the weekend as a Black Sea export terminal returned to service, a shift Yahoo Finance and Barchart flagged as the proximate driver. Whichever mattered more, the New York session added nothing either way.
1.9% is Monday's headline loss in gold, which settled at 4,622.50. That number hides a round trip. Gold fell to a session low near 4,400 in the hours before New York opened, continuing Friday's crash, then rallied more than 9% intraday to a peak near 4,837 by mid-morning before fading back through the afternoon into the close.
Friday's crash was the proximate cause still working through the market: silver hit a record 121.67 dollars on Thursday, then fell as low as 78 dollars over the following two sessions after Trump named Kevin Warsh his pick for Fed chair and CME Group raised margin requirements to 8% on gold futures and 15% on silver, forcing what Morgan Stanley estimated near 3.5 billion dollars of SLV selling and 650 million of GLD selling, per BullionVault's reporting. Monday's session was still absorbing that liquidation, not reacting to anything new.
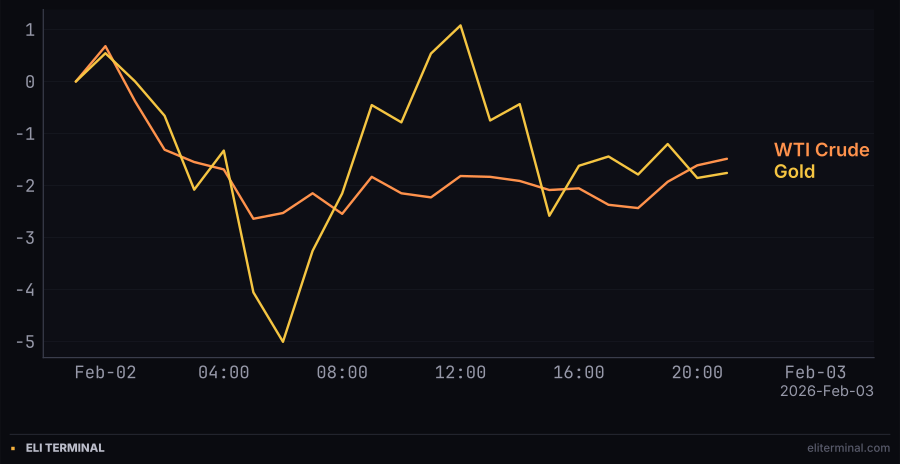
Both fell together overnight. Only gold gave back a violent midday round trip before the close.
28.5% is where a Polymarket contract on Warsh being confirmed as Fed chair and rates reaching 2.5% or lower in 2026 has sat since Saturday, little changed from the 21.5% it carried the two sessions before Trump's nomination and still within the range that contract held through most of January. If traders read Warsh as a hawkish pick, that number would have fallen, not held.
The gold and silver selloff instead traces to CME's margin increase forcing leveraged funds to unwind positions, a mechanical trigger with no relationship to what the market expects Warsh to do with rates once seated. The narrative and the mechanism are pulling in different directions, and Monday's price action followed the mechanism.
The federal government has been in a partial shutdown since Saturday, the second of the year, after the Senate passed a funding package Friday on a 71-29 vote that also extends stopgap funding for the Department of Homeland Security through February 13. The House was scheduled to vote Tuesday on the same package, per CNBC's reporting on the Senate vote. Four sessions of the Senate already having acted gave Monday's buyers one less overhang to weigh against a clean manufacturing beat.